Search results for august
august community
One keyword maps to one global community path.
People
Not Found
Tweets including august

August core goods orders +1.6% m/m vs. +0.6% est. & 0.6% prior … core cap goods shipments +0.6% vs. +0.8% est. & +1.4% prior

August durable goods orders +0.0% m/m vs. -0.3% est. & +0.9% prior … orders ex-transportation +0.3% vs. +0.6% est. & +0.7% prior

August new home sales rose +6.4% m/m vs. +1.3% est. & -4.3% prior (revised up from -10.5%) … median new home price +0.4% m/m to $393,700; average selling price at $478,700
Show more


August Battery data from CABIA:
LFP 78.2% & NCM 21.5% among auto battery
99.96% LFP among ESS
Overall 82.4% LFP & 17.4% NCM
Total production reached 237 GWh (up 69.8% YoY & 8.8% Mom)
Accumulated in 2026 1523.9 GWh, up 57% YoY
Large battery pack per EV, more eHDT & ESS -> huge surge in demand for battery globally even if NEV sales is not increasing drastically.
Show more


August’s Photos of the Day encompassed bursts of color in Nebraska's sky, a flamboyance of flamingos, and seal pups taking their first dips in the ocean. Nat Geo’s photography department picked 23 classic images to highlight alongside the stories behind them. 🔗
Show more

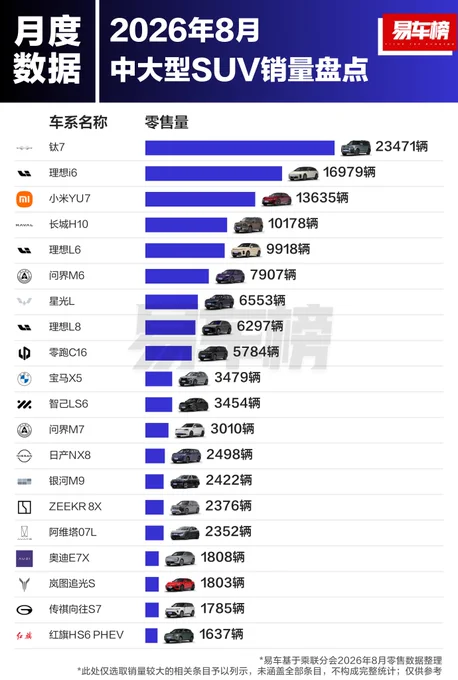
August SUV sales for large flagship & medium-Large. Dominated by domestic NEVs. Only AITO M9 & NIO ES9 are all 10k for flagship SUVs. BYD is represented by Da Tang & Denza N8L & N9 on this list.
Tai-7 is best selling med/large SUV, well ahead of both Li Auto i6 & Xiaomi Yu7.
It's really the start of BYD models.
Show more

August jobless rates down in 8 states; payroll jobs up in 4 states #BLSData#
August industrial production (top pane) flat m/m vs. +0.3% est. & +0.2% prior … manufacturing production (bottom pane) -0.3% vs. +0.3% est. & +0.2% prior

August pending home sales moved further in negative territory on a year/year basis

August pending home sales +0.3% m/m vs. -0.1% est. & -2.6% prior (revised down from -2.3%)
