Jesse Livermore
@Jesse_Livermore
Trader, Speculator, Bucketeer
加入 December 2010
11.2K 正在關注 104K 粉絲
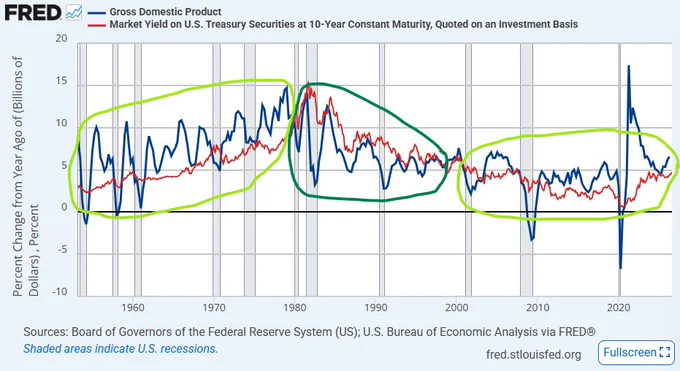
The thumbrule that says that the 10-year treasury yield should be roughly equal to nGDP growth is based on a cherry-picked historical anomaly. It only held true during a period in the mid-to-late 1990s, in the aftermath of the Volcker monetary tightness (when the 10-yr rate was actually higher than nGDP growth). During the expansions of the 1950s, 1960s, 1970s, 2000s, and 2010s, the 10-year was typically 2%-3% points below nGDP growth. Today, that would suggest a 4%-5% yield.
The claim that rates should be 6%-7% today b/c that's where nGDP growth is are even more dubious when considering current wage growth. For most of post-war history, 10-yr rates were 2%-3% below aggregate wage (COE) growth. That includes the boom of the late 1990s, which saw very strong growth. The numbers on that front may improve from here, but so far, they've been quite weak, which would suggest a 10-yr yield well below current levels.
顯示更多