
LIWEI_TW Capital
@LIWEI_TWCapital
Even a great company is only worth recommending at the right price. Every trading idea shared should deliver real, actionable value when it matters most.
加入 January 2024
427 正在關注 12.2K 粉絲
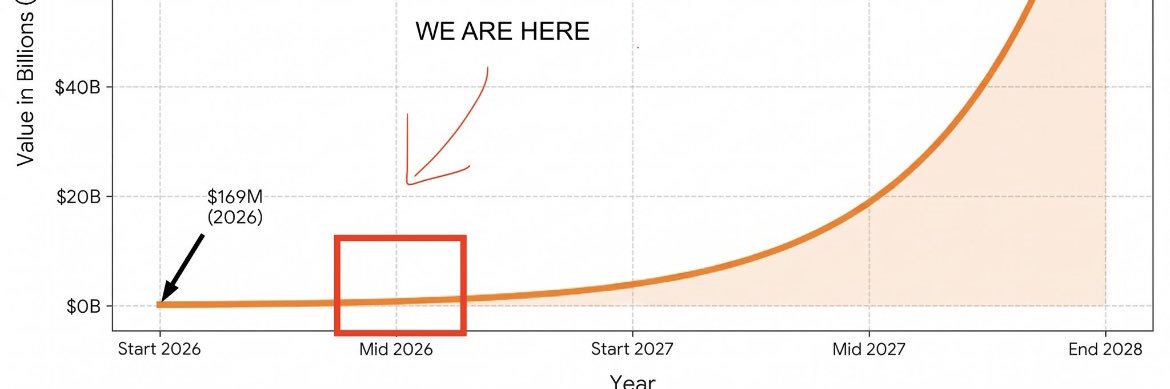
MssCorp (TWE: 6830) Serenity High Conviction Bet(analysis fully grounded in TSMC’s latest public expansion plans and 2026 industry data):
– this is the functional monopoly in CPO/SiPh inspection (90%+ share targeted, pricing power is real). Long list of customers ($TSM, $NVDA, $AAPL, $AMAT , $LRCX, $ASML , $INTC ) all need to go through them for yields. NVIDIA dedicated AI Chip Zone in US facility = strategic lock-in.
-GS CPO TAM still the anchor: $91B by 2028.
-TSMC CoWoS doubling to 130k-140k wafers per month by end-2026 via AP7 Chiayi (world’s largest advanced packaging hub, CoPoS pilot 2026/volume ramp 2027-28) + AP8 Tainan (P1/P2) + AP5/AP6 upgrades. We are still in the frontrunning window.
Pure TSMC fab expansion model only — no NVIDIA exclusive assumed. Factory-by-factory HG demand: HG is specialized QA/FA tool (not standard per-line gear). Base Assumption~60 units per major packaging “module group” (20 front / 20 mid / 20 back).
Using latest TSMC 2026 data:
AP6 (Longtan/Taichung): Operating + upgrade → ~30 units / MssCorp 25-30 units
AP7 Chiayi: World’s largest, CoPoS pilot → ~45-120 units / MssCorp 40-100 units
AP8 Tainan (P1-P2): Construction/ramp → ~120 units/ MssCorp 100-110 units
AP8 later phases + AP9: 2028+ planning → ~240-260 units / MssCorp 200-220 units
TSMC only total: ~435-530 units / MssCorp 365-460 units
Updated HG model (reflecting monopoly + pricing power): Industry total demand 130-200 units 26-30. With 90%+ monopoly → MssCorp ships 120-180 units (spares + repeat buys). ASP NT$60M (pricing power) + GM 60-75%.
HG contribution build (NT$ bn, cumulative 2026-2030): Equipment sales + Recurring services/consumables (25–45% of equipment value over 5 years) + IP licensing (20–35% of equipment rev, 80-90% margin). Total HG contribution NT$9.5bn–NT$13bn. Core MA/FA business growing 20-30% CAGR from NT$22B 2025 base on top.
Revenue path (NT$ bn):
2026: 30–38
2027: 45–62
2028: 65–88
2029-30+: 180–240/yr (normalized)
Mix shifts hard to high-margin equipment + recurring + IP as CPO goes volume
Share count 51.78M. With the structural monopoly in a critical yield choke-point + TSMC/NVIDIA tailwinds, long-term normalized forward EPS can realistically reach NT$180–240 (US$5.6–7.5).
40–60x forward P/E (standard for AI/SiPh leaders with real moats) → target NT$5,000+. Current MC ~$1.2–1.4B.
顯示更多