Search results for 0725梅田高市やめろスタンディング
0725梅田高市やめろスタンディング community
One keyword maps to one global community path.
People
Not Found
Tweets including 0725梅田高市やめろスタンディング


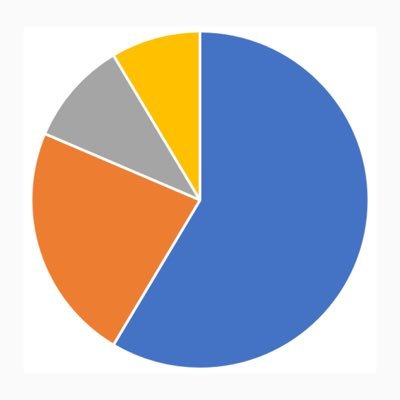
Projected Muslim Population in European Countries in 2050
🇸🇪 Sweden: 30.6%
🇦🇹 Austria: 19.9%
🇩🇪 Germany: 19.7%
🇧🇪 Belgium: 18.2%
🇫🇷 France: 18%
🇬🇧 UK: 17.2%
🇳🇴 Norway: 17%
🇩🇰 Denmark: 16%
🇳🇱 The Netherlands: 15.2%
🇫🇮 Finland: 15%
🇮🇹 Italy: 14.1%
🇨🇭 Switzerland: 12.9%
🇧🇬 Bulgaria: 11.6%
🇬🇷 Greece: 9.7%
🇪🇸 Spain 7.2%
🇸🇮 Slovenia: 5.2%
🇭🇺 Hungary: 4.5%
🇮🇪 Ireland: 4.4%
🇵🇹 Portugal: 2.5%
🇭🇷 Croatia: 2.1%
🇨🇿 Czech Republic: 1.2%
🇪🇪 Estonia: 1%
🇷🇴 Romania: 0.9%
🇸🇰 Slovakia: 0.7%
🇱🇻 Latvia: 0.4%
🇱🇹 Lithuania: 0.2%
🇵🇱 Poland: 0.2%
(Pew Research Center, 2017, high migration scenario)
Show more


Last wk, oil +9% & ylds +11-26 bps across 2/30 curve w/ S&P/Nas/R2K -0.3%/-0.7%/-2.4%. This wk, I am watching reaction to 1) oil/rates, 2) calls to slow down AI development & 3) Fed on 9/16. I remain on the cautious side till US mid-terms on 11/3.
This weekend, the CEO of Anthropic called for a slowing of frontier model development over safety concerns. This follows comments along similar lines by the CEO of OpenAI to employees last week if other companies were willing to do the same thing.
The fundamental issues I have with this is 1) foreign adversaries would welcome the US slowing down AI development, 2) I view this as an attempt to slow down open-weight model development which would help the market dominance of OpenAI and Anthropic which are currently in the lead and 3) I do not see other companies agreeing to anything that slows down progress catching up to these two market leaders. Having said that, I could see 3rd party evaluators to limit liability risk going forward and some sort of executive order from the White House. But I hope the longer-term result of these actions is broadly distributed personal AI capabilities for all individuals versus having it become concentrated in the hands of a few companies.
Along this vein of AI competition, after releasing their paid API of Muse Spark 1.3 two weeks ago with open-weight versions coming later, $Meta launched their personal AI agent Muse last week with the stock gaining 5%. With 3.6 billion daily active users, a hit product could yield large results. Meta is increasingly showing other ways they can monetize their AI capex spend. This should help the stock to re-rate from a 17x CY27 PE to a multiple closer to peers trading in the low 20s. Meta Connect on September 23–24 is another potential catalyst given their leading frontier model Watermelon should be coming at the latest by October.
On the front of broadly distributed AI capabilities, $AAPL stock gained 4% last week on their new product launch. The foldable Duo will provide a personalized AI agent in your pocket with a 50% larger screen than a Pro Max. I continue to see a big upgrade cycle next year. The change from a 4” screen to 5.5” screen with the iPhone 6 drove revenue growth from 7% in FY14 to 28% in FY15. The Android ecosystem has had a foldable Samsung phone since 2019.
As for the Fed on Wednesday, I believe Warsh will raise by 25 bps and echo his hawkish statements from Jackson Hole on August 28th that “Price stability is not self-executing… 65 months of sustained, elevated inflation sits squarely with the Central Bank.” The ECB statement last week when they hiked might provide some hints: “For inflation excluding energy and food, the baseline foresees 2.5% in 2026, 2.6% in 2027 and 2.3% in 2028. Compared with June, the baseline projection for inflation in 2026 is unchanged, while it has been revised up for 2027 and 2028… The outlook remains highly uncertain, with risks to the upside for inflation and to the downside for economic growth.”
In summary, my caution between now and the US mid-terms on 11/3 remains for reasons I have fleshed out in prior posts including:
1. Don’t fight the Fed: The market historically under-performs during a hiking cycle with the bond market discounting 2 raises by year-end and 3.5 raises by mid-June of 2027.
2. Seasonal headwinds: September is down -0.5% on average and up only 48% of the time since 1957.
3. Historical volatility: S&P drawdowns of 10% between 7/31 and 11/9 have occurred in the lead-up to mid-terms since 1990.
4. Regulatory friction: There is bipartisan pushback against datacenter expansion that could hurt the AI buildout in the near-term.
5. Geopolitical risk: Despite US efforts to de-escalate, I believe Iran drags out hostilities at least through the 11/3 US mid-terms, keeping oil prices elevated.
6. Macroeconomic pressure: Long-term government bond yields are hitting multi-decade highs for several countries, slowing down growth and providing a reasonable alternative to stocks.
I believe in not fighting the Fed, the bond market or seasonality. I like the odds stacked in my favor which should improve at least seasonally following the mid-terms.
Show more
💶 Government budget balance in EU countries (2025, % of GDP)
1. 🇨🇾 Cyprus: +3.6%
2. 🇩🇰 Denmark: +2.9%
3. 🇬🇷 Greece: +2.0%
4. 🇮🇪 Ireland: +1.8%
5. 🇵🇹 Portugal: +0.7%
6. 🇳🇱 Netherlands: −1.6%
7. 🇸🇪 Sweden: −1.6%
8. 🇱🇺 Luxembourg: −1.8%
9. 🇱🇹 Lithuania: −1.8%
10. 🇪🇪 Estonia: −2.0%
11. 🇲🇹 Malta: −2.1%
12. 🇨🇿 Czechia: −2.2%
13. 🇪🇸 Spain: −2.4%
14. 🇸🇮 Slovenia: −2.5%
15. 🇱🇻 Latvia: −2.5%
16. 🇩🇪 Germany: −2.9%
17. 🇭🇷 Croatia: −3.0%
🇪🇺 EU: −3.1%
18. 🇮🇹 Italy: −3.1%
19. 🇫🇮 Finland: −3.8%
20. 🇧🇬 Bulgaria: −4.0%
21. 🇦🇹 Austria: −4.1%
22. 🇸🇰 Slovakia: −4.4%
23. 🇭🇺 Hungary: −4.7%
24. 🇫🇷 France: −5.1%
25. 🇧🇪 Belgium: −5.2%
26. 🇵🇱 Poland: −7.2%
27. 🇷🇴 Romania: −7.8%
Only five EU countries ran a budget surplus in 2025: Cyprus, Denmark, Greece, Ireland and Portugal.
Surplus (+) or deficit (−) as a share of GDP.
Source: Eurostat
Show more

BREAKING: US stock market futures rise as traders buy the dip in technology stocks and oil prices fall below $90/barrel:
1. S&P 500: +0.7%
2. Nasdaq 100: +0.5%
3. Dow Jones: +1.1%
4. WTI Crude: -2.9%
5. Brent: -3.0%
6. Gold: +1.1%
The S&P 500 is set to open above 7,400.
Show more

All my oQe models have been updated with Improved oQe Quantization, available from oMLX 0.7.1. Compared with the previous oQe builds, KL divergence is 11.6–18.1% lower on code and 10.2–13.8% lower on prose, so please give them a try. The full model list is below.
KL divergence from the original BF16 model (mean, lower is better)
- Qwen3.8-27B oQ4e: code 0.0143 → 0.0117 (-18.1%), prose 0.0696 → 0.0600 (-13.8%)
- Qwen3.8-Flash-Next oQ4e: code 0.0877 → 0.0776 (-11.6%), prose 0.1909 → 0.1713 (-10.2%)
What's new
- Below oQ4, the Engram and N-gram tables stay at 4 bits and are left out of the bit budget. oMLX can serve these tables from SSD instead of memory, so the full bit budget goes to the rest of the model.
- Model cards now show the bit distribution and storage breakdown.
If you downloaded an earlier oQe build, please re-download it.
Improved oQe models (69)
- Qwen3.8-Flash-Next: 2.5 · 2.7 · 3 · 3.5 · 4 · 6 · 8 bits
- Qwen3.8-Flash-Next FP16: 2.5 · 3 · 3.5 · 4 bits
- Qwen3.8-27B: 2.5 · 3 · 3.5 · 4 · 6 · 8 bits
- Qwen3.6-35B-A3B: 2.5 · 3 · 3.5 · 4 · 6 · 8 bits
- GLM-5.3-Flash: 2 · 2.5 · 3 · 3.5 · 4 · 5 · 6 bits
- DeepSeek-V4.1-Flash: 2 · 2.5 · 3 · 4 bits
- DeepSeek-V4-Flash-0731: 2.5 · 2.7 · 3 · 3.5 · 4 bits
- gemma-4-31B-it: 2.5 · 3 · 3.5 · 4 · 6 · 8 bits
- gemma-4-26B-A4B-it: 2.5 · 3 · 3.5 · 4 · 6 · 8 bits
- gemma-4-12B-it: 2.5 · 3 · 3.5 · 4 · 6 · 8 bits
- clef: 2.5 · 3 · 3.5 · 4 · 6 · 8 bits
- clef-flash: 2.5 · 3 · 3.5 · 4 · 6 · 8 bits
Show more
The global debt crisis is set to get even worse:
The US fiscal deficit is projected to widen to -6.1% of GDP in 2027, its largest since 2012, excluding the pandemic years of 2020 and 2021.
This will be the biggest deficit as a % of GDP among the 5 major developed economies, including the UK, Germany, France, and Japan.
Furthermore, Germany's deficit is expected to widen from -2.7% of GDP in 2025 to -4.1% in 2027, its largest since 2010, excluding the 2020 pandemic.
Japan's fiscal deficit is estimated to more than triple, from -0.7% to -2.5% of GDP, its largest since 2022.
The UK is the only economy expected to improve its fiscal position, with its deficit narrowing from -4.3% in 2025, to -3.1% of GDP next year, while France's budget gap is projected to widen to -5.2%.
Deficit spending is only accelerating.
Show more

🔎 How long unemployed people have been looking for work (median, 2025)
1. 🇿🇦 South Africa: 12+ months
2. 🇸🇰 Slovakia: 12+ months
3. 🇬🇷 Greece: 12+ months
4. 🇮🇹 Italy: 12+ months
5. 🇧🇬 Bulgaria: 9.3 months
6. 🇭🇷 Croatia: 8.0 months
7. 🇱🇹 Lithuania: 7.9 months
8. 🇷🇴 Romania: 7.8 months
9. 🇵🇹 Portugal: 7.6 months
10. 🇱🇻 Latvia: 6.9 months
11. 🇨🇭 Switzerland: 6.7 months
12. 🇨🇿 Czechia: 6.5 months
13. 🇱🇺 Luxembourg: 6.0 months
14. 🇭🇺 Hungary: 5.9 months
15. 🇧🇪 Belgium: 5.7 months
16. 🇵🇱 Poland: 5.6 months
17. 🇪🇸 Spain: 5.5 months
18. 🇩🇪 Germany: 5.3 months
19. 🇪🇪 Estonia: 5.1 months
20. 🇯🇵 Japan: 4.9 months
21. 🇸🇮 Slovenia: 4.8 months
22. 🇦🇹 Austria: 4.8 months
23. 🇨🇾 Cyprus: 4.6 months
24. 🇳🇿 New Zealand: 4.5 months
25. 🇬🇧 UK: 4.5 months
26. 🇫🇮 Finland: 4.3 months
27. 🇫🇷 France: 4.2 months
28. 🇲🇹 Malta: 4.0 months
29. 🇹🇷 Türkiye: 3.6 months
30. 🇸🇪 Sweden: 3.5 months
31. 🇦🇺 Australia: 3.4 months
32. 🇮🇪 Ireland: 3.4 months
33. 🇨🇴 Colombia: 2.8 months
34. 🇳🇴 Norway: 2.7 months
35. 🇮🇱 Israel: 2.6 months
36. 🇩🇰 Denmark: 2.6 months
37. 🇰🇷 South Korea: 2.6 months
38. 🇮🇸 Iceland: 2.6 months
39. 🇳🇱 Netherlands: 2.5 months
40. 🇨🇦 Canada: 2.4 months
41. 🇺🇸 United States: 2.2 months
42. 🇲🇽 Mexico: 1.2 months
In South Africa, Slovakia, Greece and Italy, half of all unemployed people have been looking for work for more than a year.
At the other end, the typical job seeker in Mexico has been searching for just 1.2 months, and in the United States 2.2 months.
Long job searches are most common in southern and eastern Europe, while North America, Norway, Denmark and Iceland have some of the shortest.
Median time already spent looking for work by people who are currently unemployed: half have been searching longer, and half for less.
Source: OECD, unemployment by duration
Show more

Spain Industrial Production (M/M) Aug: -0.7% (est -0.5%; prev 0.6%)
- Industrial Output SA (Y/Y): 1.5% (est 2.4%; prev 2.3%; prev R 2.5%)
- Industrial Output NSA (Y/Y): 1.6% (prev 2.6%; prev R 2.8%)