Search results for 0815新宿ペンライトアクション
0815新宿ペンライトアクション community
One keyword maps to one global community path.
People
Not Found
Tweets including 0815新宿ペンライトアクション

Last wk, SPX/Nas/R2K +0.5%/+0.8%/-1.5% w/ oil -4%. But a hawkish Warsh on Friday led to a bear flattening of the yield curve. Despite $NVDA guide of 70% CY27 rev growth vs consensus of 47%, SOX Index -2.3% while software $IGV +5.9% on solid earnings.
In general, many AI investors have been bullish on semiconductors and bearish on software on the belief that AI will displace many point solution software companies. This is why the SOX index is up 62% YTD and IGV is still only up 4% YTD versus the S&P +13%. Situational Awareness was the poster child for this type of positioning.
But since the unwinding of the Momentum trade which started on 6/22 (I wrote about these concerns on 6/20), IGV has rallied 25% while the SOX Index has declined 22% through 8/28. For perspective, the Morgan Stanley Momentum index (momentum long performance minus momentum short performance) from 6/22-8/28 is down 36% while their more concentrated TMT index is down 54%. But a bullish twist on AI for the software sector introduced recently is that AI agents will access software tools ~10-100x more often than humans.
On 8/6, $TEAM, which was in the bucket of software names widely considered at risk of being replaced by AI, rallied 35% the next day in reaction to solid earnings & outlook.
Then on 8/13, $WDAY rallied 18% on the news that private equity firm Silverlake might be pursuing an acquisition which I wrote probably put a floor underneath software. Workday was also supposed to be in the AI crosshairs and private equity has higher bars to clear given their use of leverage and holding period than a typical investor.
Then on 8/26, $CRM reported solid results, guidance and a deal with Anthropic (in which they also first invested in May of 2023.) The stock was up 23% in reaction the next day. This seemed to be a strong counterpoint to the SaaS-pocalypse worries. This strategic alliance allows users to execute actions natively inside Claude without needing to open traditional software screens. Salesforce also seems to be changing how they charge customers with fees more related to customer use and benefits to their business.
Then on 8/27, Workday reported results which were good enough but arguably acquisition prospects drove more of the stock reaction of +6% the next day from the slightly down opening price.
Historically, system of record, security and gaming software have been the only three areas I have liked within software. I now wonder whether the fundamental implications of Atlassian, Workday and Salesforce are supportive of the technical reactions in the software stocks as a group as agentic AI continues to ramp.
So how do I square this with my concerns that the rapidly escalating amounts spent on AI by corporations has to come from somewhere? Annualized revenue run-rates for Anthropic and OpenAI have ramped from $29B to start the year to $105B just 7 months later. Software spending globally excluding AI was roughly $1 trillion in 2025. But IT services at $1.7 trillion is a bigger category which I believe still has risk. And finally, knowledge worker compensation is an even bigger category where disruption would be even less noticeable at an estimated $35-50 trillion in 2025 or roughly 30% of the global workforce.
Looking forward, the deal on Friday for Venezuelan oil fields that hold the largest crude reserves in the world at 17-18% should get us off to a positive start to the week with declining oil prices. But a bit further out: 1) “Don’t Fight the Fed” given I believe a hike is likely on 9/16 because the 10/28 mtg is right before mid-terms, 2) September has the poorest seasonality of all months, 3) there is even worse seasonality than normal during mid-term election years (see prior posts for more detail) and 4) recent bipartisan pushback against datacenter expansion (one of the few things both sides seem to agree on though I believe this is wrong and hope it will change with more education) puts pressure on the AI infrastructure names.
As Warren Buffett says, the market has to keep pitching but you do not need to swing.
Show more
New FFmpeg point releases: 8.1.2, 8.0.3, 7.1.5, 6.1.6, 5.1.10 and 4.4.8 are now available.
Includes fixes for issues reported to ffmpeg-security

UK Construction Output (M/M) Sep: 0.8% (est -0.1%; prev -0.2%; prev R -0.5%)
- Construction Output (Y/Y): -1.5% (est -2.2%; prev –1.8%; prev R 1.9%)

UK (Sep) CONSTRUCTION OUTPUT (MOM) ACTUAL: 0.8% VS -0.2% PREVIOUS; EST: 0.0%
UK (Sep) CONSTRUCTION OUTPUT (YOY) ACTUAL: -1.5% VS -1.8% PREVIOUS; EST: -2.1%
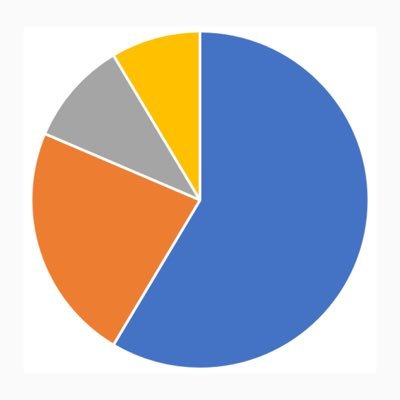
☕ Countries that drink the most coffee
Share of global coffee consumption, 2025/26:
1. 🇺🇸 United States: 14.7%
2. 🇧🇷 Brazil: 12.8%
3. 🇩🇪 Germany: 6.4%
4. 🇯🇵 Japan: 3.8%
5. 🇵🇭 Philippines: 3.8%
6. 🇨🇳 China: 3.7%
7. 🇨🇦 Canada: 2.9%
8. 🇫🇷 France: 2.9%
9. 🇻🇳 Vietnam: 2.8%
10. 🇮🇩 Indonesia: 2.8%
11. 🇷🇺 Russia: 2.6%
12. 🇬🇧 United Kingdom: 2.6%
13. 🇪🇹 Ethiopia: 2.6%
14. 🇮🇹 Italy: 2.4%
15. 🇪🇸 Spain: 2.0%
16. 🇰🇷 South Korea: 1.8%
17. 🇲🇽 Mexico: 1.8%
18. 🇵🇱 Poland: 1.6%
19. 🇦🇺 Australia: 1.5%
20. 🇨🇴 Colombia: 1.3%
21. 🇳🇱 Netherlands: 1.2%
22. 🇩🇿 Algeria: 1.2%
23. 🇸🇪 Sweden: 1.1%
24. 🇹🇷 Türkiye: 1.0%
25. 🇮🇳 India: 0.9%
26. 🇸🇦 Saudi Arabia: 0.8%
27. 🇷🇴 Romania: 0.7%
28. 🇨🇭 Switzerland: 0.7%
29. 🇪🇬 Egypt: 0.7%
30. 🇦🇹 Austria: 0.6%
The world drinks 173.5 million 60-kg bags of coffee a year. Europe accounts for 32%, Asia-Pacific 23% and North America 21%.
Green bean equivalent consumption, 2025/26 marketing year (October–September in most countries). These are country totals, not per person.
Source: USDA Foreign Agricultural Service, European Coffee Federation
Show more

Tesla is still dominating. In the first half of 2026, they secured over 52% of the U.S. EV market.
1. Tesla: 52.3% — 242,100 units sold
2. Chevrolet: 6.1% — 28,267
3. Hyundai: 5.8% — 26,936
4. Cadillac: 4.7% — 21,855
5. Rivian : 4.7% — 21,770
6. Toyota: 4.7% — 21,767
7. Ford: 3.6% — 16,606
8. Kia: 2.7% — 12,627
9. BMW: 2.4% — 10,790
10. Subaru: 2.2% — 10,064
11. Honda: 1.8% — 8,407
12. Lexus: 1.7% — 7,814
13. GMC: 1.4% — 6,645
14. Lucid: 1.1% — 5,208
15. Volvo: 0.9% — 3,964
16. VW: 0.8% — 3,768
17. Mercedes: 0.6% — 3,010
18. Porsche: 0.6% — 2,967
19. Other Brands: 0.6% — 2,596
20. Nissan: 0.4% — 1,774
21. Audi: 0.4% — 1,697
22. Genesis: 0.1% — 560
23. Dodge: 0.1% — 534
24. Jeep: 0.1% — 418
25. Mini: 0.1% — 307
26. Acura: 0.0% — 108
(Data Via Cox Automotive Q2 2026 EV sales)
Show more


CHOOSE YOUR FIGHTER
Warren Buffett vs Stanley Druckenmiller
Buffett stepped down as Charman of Berkshire Hathaway $BRK.B today. Druckenmiller has never had a losing year in more than 30 years.
Here are their full portfolios as of Q2 2026.
BERKSHIRE HATHAWAY
- Apple $AAPL: 22%
- American Express $AXP: 17%
- Google $GOOGL: about 12.6% across both share classes
- Coca-Cola $KO: 11%
- Bank of America $BAC: 9.2%
- Chevron $CVX: 4.7%
- Occidental $OXY: 4.3%
- Chubb $CB: 3.9%
- Moody's $MCO: 3.7%
- Kraft Heinz $KHC: 2.6%
- DaVita $DVA: 2.1%
- Delta $DAL: 1.8%
- SiriusXM $SIRI: 1.2%
- VeriSign $VRSN: 0.8%
- Kroger $KR: 0.7%
- Liberty Live $LLYVA: about 0.6% across both share classes
- Ally $ALLY: 0.4%
- Lennar $LEN: 0.4%
- New York Times $NYT: 0.4%
- Capital One $COF: 0.2%
- Louisiana-Pacific $LPX: 0.1%
- Nucor $NUE: 0.1%
- Macy's $M: 0.1%
- NVR $NVR
- Jefferies $JEF
- D.R. Horton $DHI
DUQUESNE FAMILY OFFICE
- Natera $NTRA: 17%
- Insmed $INSM: about 5.7% in shares and calls
- Taiwan Semi $TSM: 5.4%
- Brazil ETF $EWZ: about 5.1% in shares and calls
- Amazon $AMZN: about 4.6% in shares and calls
- STMicro $STM: 4.5%
- S&P 500 Equal Weight $RSP: about 3.7% in calls and shares
- Fox $FOXA: about 2.8% across both share classes
- YPF $REPYY: 2.7%
- CDW $CDW: about 2.7% in shares and calls
- BBB Foods $TBBB: 2.3%
- Google $GOOGL: 2.3%
- Seagate blockstack:native: 2.3%
- United Airlines $UAL: 2.1%
- Sea $SE: 2.0%
- NewAmsterdam Pharma $NAMS: 2.0%
- Russell 2000 ETF $IWM: 1.9% in calls
- Sandisk $SNDK: 1.5%
- Revolution Medicines $RVMD: 1.4%
- S&P 500 ETF: 1.3% in calls
- Bitdeer: 1.2%
- CRH: 1.1%
- Delta: 1.1%
- Tesla $TSLA: 1.0% in calls
- Fluor: 1.0%
- D.R. Horton: 0.9%
- Coupang: 0.9%
- AMD: 0.8%
- Palo Alto Networks: 0.8%
- Cleveland-Cliffs: 0.8%
- Hut 8: 0.7%
- Caris Life Sciences: 0.6%
- Argentina ETF: 0.6%
- Woodward: 0.5%
- Meta: 0.5% in calls
- Nuvation Bio: 0.5%
- Protagonist Therapeutics: 0.5%
- Roku: 0.5%
- Cavco: 0.5%
- ADMA Biologics: 0.4%
- Hyperliquid Strategies: 0.4%
- Rambus: 0.4%
- Rhythm Pharmaceuticals: 0.4%
- Champion Homes: 0.4%
- Daktronics: 0.4%
- PureCycle: 0.4%
- Southern Copper: 0.4%
- Linde: 0.4%
- Entegris: 0.4%
- Teva: 0.4%
- Unity: 0.4%
- Aeva: 0.4%
- Riot Platforms: 0.4%
- Qnity Electronics: 0.4%
- Equinix: 0.4%
- Lam Research: 0.4%
- Definium Therapeutics: 0.3%
- Belite Bio: 0.3%
- 10x Genomics: 0.3%
- Wabtec: 0.3%
- Eli Lilly: 0.3%
- Xenon Pharmaceuticals: 0.3%
- Olema Pharmaceuticals: 0.2%
- Repligen: 0.2%
- Rocket Companies: 0.2%
- Baidu: 0.2%
- Arm: 0.2%
- Carvana: 0.2%
- Reddit: 0.2%
- Alcoa: 0.2%
- Thermo Fisher: 0.2%
- Danaher: 0.2%
- F5: 0.2%
- Vista Energy: 0.2%
- Skeena Resources: 0.2%
- JBS: 0.1%
- Monte Rosa Therapeutics: 0.1%
- Relay Therapeutics: 0.1%
- DBV Technologies: 0.1%
- CCC Intelligent Solutions: 0.1%
- UWM Holdings: 0.1%
- Navitas Semiconductor: 0.1%
- Solstice Advanced Materials: 0.1%
- FTAI Aviation: 0.1%
- Beam Therapeutics: 0.1%
- Aurora Innovation: 0.1%
- IREN: 0.1%
- Grupo Financiero Galicia: 0.1%
- Wave Life Sciences: under 0.1%
Both own Google, Delta and D.R. Horton. Neither owns Nvidia $NVDA.
Show more


MACY'S $M Q2’26 EARNINGS HIGHLIGHTS
🔹 Revenue: $4.9B (Est. $4.83B) 🟢; +1.1% YoY
🔹 Adj. EPS: $0.63; incl. $0.23 tariff refunds
🔹 Adj. EPS ex-Refund: $0.40 (Est. $0.37) 🟢
🔹 GAAP EPS: $0.62; +100% YoY; incl. refunds
🔹 Adj. EBITDA: $457M; incl. tariff refunds
Raises FY26 Guide:
🔹 Revenue: $21.7B-$21.8B (Est. $21.91B) 🔴; from $21.5B-$21.75B
🔹 Adj. EBITDA Margin: 7.8%-8.0% (Est. 8.1%) 🔴; from 7.7%-7.9%
🔹 Adj. EPS: $2.15-$2.35 (Est. $2.25) 🟡; from $2.00-$2.20
🔹 Comparable Sales Change: 1.0% to 1.5%; from 0.5% to 1.2%
Other Q2 Metrics:
🔹 Comparable Sales: +2.7%
🔹 Go-Forward Business Comps: +2.8%
🔹 Macy's Comps: +1.1%
🔹 Bloomingdale's Comps: +11.3%
🔹 Bluemercury Comps: +6.2%
🔹 Gross Margin: 41.5%; incl. 180 bps refunds
Key Updates:
🔸 Tariff refunds: $98M of IEEPA refunds received in Q2 and $18M after quarter end ($116M total); the net benefit was $84M pre-tax, $0.23 per share after tax and 180 bps of gross margin — excluding it, adjusted EPS was $0.40, +14% YoY, and gross margin was up 10 bps; the FY26 guide reinvests the majority of the refunds, with ~$0.05 per share flowing through to adjusted EPS
Comments:
🔸 “The investments we're making are driving results across our portfolio, from the continued outperformance of our Reimagine 200 Macy’s stores, to meaningful double-digit growth at Bloomingdale’s and another solid quarter at Bluemercury.”
Show more


📌 VI. Trigger Matrix (V2.0 – Observation Status Log)
Observation Item Current Value Threshold Status Consecutive Days/Trend
Super-Capital Concentration Risk 9.3 8.0 ESCALATION ↑ 1 day (new)
AI Governance Risk 8.8 8.0 ESCALATION ↑ 1 day (new)
Resilience Ratio 0.63 0.70 ESCALATION ↑ 4 days
US-Iran Deal Signing Status 接近 Formal Signing WATCH —
Brent Crude Oil Price 3-mo low — THRESHOLD_CROSSED 1 day
New Ebola Health Zone (DRC) Confirmed spread — THRESHOLD_CROSSED 3 days
EU Accession Talks Launched — THRESHOLD_CROSSED 1 day
Items Near Threshold (Elevated Observation):
Observation Item Current Value Threshold Current Status
• Formal signing of US-Iran deal 接近 Formal Signing ALERT
• SpaceX market cap stability Above $2T Drop below $2T WATCH
• OpenAI probe scope expands Multi-state Federal involvement ALERT
• G7 Summit statements on AI & trade 即将 held Substantive regulatory共识 WATCH
• Cross-border Ebola spread Risk rising First邻国 confirmed case ALERT
• Clustered cases in fan zones No reports Confirmed cluster transmission WATCH
---
📅 VII. Key Observation List for the Next 72 Hours
Grade A Observations (High Impact):
Observation Item Potential Impact if Triggered
1. Formal signing of US-Iran MOU Geopolitical entropy pressure declines further, but execution risk仍需 assessed.
2. SpaceX market cap stability above $2T Test of sustainability for super-capital concentration narrative.
3. OpenAI probe expands to federal level Potential further upgrade to AI governance risk level.
4. G7 Summit statements on AI & trade First collective test of institutional response capacity.
Grade B Observations (Medium Impact):
Observation Item
1. Expansion of Ebola outbreak zone in DRC
2. Subsequent日程 for EU accession negotiations
3. Public health data during FIFA World Cup
---
📜 VIII. CRI Calculation Summary (V1.6)
Variable Weight Risk Score Weighted Contribution
V_capital 20% 9.3 1.86
V_tech 18% 8.8 1.58
V_inst 18% 8.1 1.46
V_geo 15% 7.5 1.13
V_human 10% 7.6 0.76
V_expansion 8% 7.9 0.63
V_market 6% 7.2 0.43
V_energy_price 5% 6.5 0.33
Total 100% CRI = 8.2
Calibration Notes: Added V_capital variable (weight 20%) to reflect super-capital concentration as a new structural risk dimension. V_tech上调 to 8.8 (AI governance race launch). V_geo下调 to 7.5 (US-Iran deal接近, declining war risk).
---
📌 IX. Structural Conclusion
On June 13, 2026, the global civilizational system's Resilience Ratio remains below the 0.70警戒线 for the fourth consecutive day.
What is most worth recording today is not war – but the first time in human civilization that private wealth approaches the GDP of a中等发达国家.
When a single entrepreneur owns a satellite network, rocket system, AI platform, energy network, financial capital, and global data流入口, civilization is entering a new organizational form:
Transitioning from nation-state-led civilization to platform-infrastructure-led civilization.
If the core question of the 20th century was "How to constrain state power?", then the core question of the latter half of the 21st century may well become "How to govern super-platform power."
Show more

US INFLATION SURGE HITS TRANSPORTATION, FOOD AND ELECTRONICS
October's hot CPI report reveals broad-based price pressures rather than isolated spikes.
🔸 Transportation: Intracity fares +6.6%, the biggest increase since September 2020.
🔸 Food: Baby food and formula +5.1% (record high), margarine +3.2%, sauces and gravies +2.6%, butter and margarine +2.0%, processed seafood +1.8%, and poultry +0.8%.
🔸 Electronics: Televisions +3.3%, the largest increase since August 2021, and smartphones +1.4%, a record monthly rise in the unadjusted series.
Persistent inflation across multiple categories strengthens the case for further Fed rate hikes.
Show more