Search results for 1977あの写真の私たち』
1977あの写真の私たち』 community
One keyword maps to one global community path.
People
Not Found
Tweets including 1977あの写真の私たち』

𝗕𝗶𝘁𝗰𝗼𝗶𝗻 𝗘𝗧𝗙 𝗙𝗹𝗼𝘄 (𝗨𝗦$ 𝗺𝗶𝗹𝗹𝗶𝗼𝗻) – 2026-09-18
TOTAL NET FLOW: 433
IBIT: 108.4
FBTC: 310.7
BITB: 9.7
ARKB: 1.9
BTCO: 0
EZBC: 0
BRRR: 0
HODL: 2.3
BTCW: 0
MSBT: 0
GBTC: 0
BTC: 0
Show more

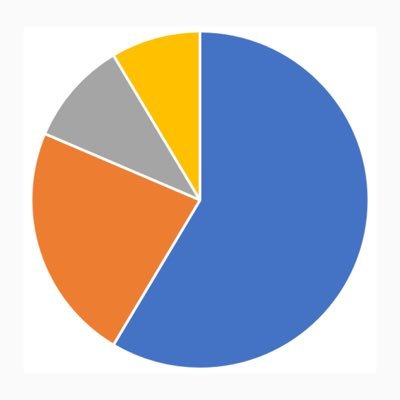
Child Poverty Rate in OECD
Share of population aged 0-17 living in poverty:
1. 🇨🇷 Costa Rica: 29.6%
2. 🇮🇱 Israel: 23.2%
3. 🇪🇸 Spain: 21.5%
4. 🇺🇸 United States: 21.1%
5. 🇧🇬 Bulgaria: 19.1%
6. 🇷🇴 Romania: 17.7%
7. 🇬🇧 UK: 15.8%
8. 🇮🇹 Italy: 14.5%
9. 🇨🇦 Canada: 14.0%
10. 🇱🇺 Luxembourg: 13.5%
11. 🇱🇹 Lithuania: 12.8%
12. 🇸🇰 Slovakia: 12.8%
13. 🇵🇹 Portugal: 12.5%
14. 🇭🇷 Croatia: 12.3%
15. 🇬🇷 Greece: 12.3%
16. 🇫🇷 France: 12.0%
17. 🇭🇺 Hungary: 11.3%
18. 🇱🇻 Latvia: 10.0%
19. 🇦🇹 Austria: 9.8%
20. 🇩🇪 Germany: 9.1%
21. 🇨🇭 Switzerland: 9.1%
22. 🇨🇿 Czechia: 8.8%
23. 🇰🇷 South Korea: 8.5%
24. 🇸🇪 Sweden: 8.4%
25. 🇳🇱 Netherlands: 8.4%
26. 🇪🇪 Estonia: 8.2%
27. 🇧🇪 Belgium: 7.9%
28. 🇵🇱 Poland: 7.8%
29. 🇳🇴 Norway: 6.9%
30. 🇮🇪 Ireland: 6.8%
31. 🇸🇮 Slovenia: 6.2%
32. 🇫🇮 Finland: 4.6%
Source: OECD Income Distribution Database. 2023 data, the latest available as of August 2026
Show more

Visa $V reports earnings after the close today, and traders now see a 78% chance it beats
It's a top 10 holding in 169 ETFs. Here are the ETFs with the most Visa exposure:
🥇 $LATR Corgi Buy Now Pay Later ETF 12.4%
🥈 $KYC Corgi Digital Banking & Fintech Infrastructure ETF 10.5%
🥉 $IYG iShares US Financial Services ETF 9.9%
4. $XLF State Street Financial Select Sector SPDR ETF 8.8%
5. $IYJ iShares US Industrials ETF 8.7%
6. $FNCL Fidelity MSCI Financials Index ETF 7.7%
7. $AKRE Akre Focus ETF 7.5%
8. $VFH Vanguard Financials ETF 7.1%
9. $RANK Defiance KSM TipRanks Analyst ETF 6.9%
10. $IPAY Amplify Digital Payments ETF 6.9%
Show more


Countries by Crude Steel Production (in Million Metric Tons)
1. 🇨🇳 China - 960.8
2. 🇮🇳 India - 164.9
3. 🇺🇸 United States - 82.0
4. 🇯🇵 Japan - 80.7
5. 🇷🇺 Russia - 67.8
6. 🇰🇷 South Korea - 61.9
7. 🇹🇷 Turkey - 38.1
8. 🇩🇪 Germany - 34.1
9. 🇧🇷 Brazil - 33.3
10. 🇮🇷 Iran - 31.8
11. 🇻🇳 Vietnam - 24.7
12. 🇮🇹 Italy - 20.7
13. 🇮🇩 Indonesia - 19.0
14. 🇹🇼 Taiwan - 17.1
15. 🇲🇽 Mexico - 13.5
16. 🇪🇸 Spain - 11.9
17. 🇨🇦 Canada - 11.5
18. 🇸🇦 Saudi Arabia - 10.8
19. 🇪🇬 Egypt - 10.6
20. 🇫🇷 France - 9.8
Source: World Steel Association (2025/2026 Data)
Show more


Last wk, $KBWB -1% despite low bank earnings expectations. AI was hit despite beat/raise from
$ASML -8%, $TSM -9% due to AI financing concerns w/ AirTrunk IPO delayed, debt getting hit w/ $CRWV -25%, Anthropic rev growth slowing & valuation looking ~$1.5T vs $2T.
Last Sunday I wrote that I was circumspect on the market. The KBWB (bank ETF) was sending a very different message than the S&P. “Any further sell-off despite trading at oversold levels last week would not be a great sign.” On Tuesday I posted on the KBWB getting hit despite these low expectations on mixed earnings results and therefore remaining circumspect. The Magnificent 7 eventually closed the week down 3.2% with the SOX Index (Semiconductors) down 11.4% driving the S&P down 1.9%.
There was rising angst on the financing part of the AI trade later in the week. This was despite 5/10/30yr yields going down 15-17 bps last week despite hotter than expected CPI/PPI. After yields initially surged, this large drop was unexpected but this also coincided with the equity market sell-off from Wednesday through Friday.
Massive external capital is needed to fund the AI infrastructure buildout. Therefore AI stocks got clobbered last week on questions around:
1) ability to raise AI public equity – Airtrunk IPO delayed till 2027 following the pulling of Firmus IPO last week
2) cost of AI debt increasing- CDS costs surging and face value of debt getting hit driving the yield to 15% for Coreweave debt
3) AI revenue growth slowing from ~145% q/q in Q2 to ~45% in Q3 for Anthropic
4) AI valuation now seen at closer to $1.5 trillion vs $2.0 trillion for some investors following Anthropic’s investor day
5) Gartner stating they expect greater than 80% of neoclouds to fold or face restructuring by 2030
6) Chinese DRAM company CXMT (-12% last week) ramping 4F technology before year-end being a threat to the current big 3 of $MU -15% last week, Samsung -18% and Hynix -24%.
As for other important macro moves last week, US Oil was +10% last week with the US dollar down 37 cents but Gold declined 1% anyway.
Thursday I posted the details around the historical precedent for a rally in the Korean Kospi Index over the following day and week given its extremely oversold levels. While the Kospi did rally on Friday +2.0%, the SOX Index was hit for 3.8% anyway and was down 11.4% for the week vs the Kospi -14.5%. While the Kospi, driven by the declines in memory stocks, is now down 40% from its 52 week high and is up 34% year-to-date, the SOX is down only 24% from its 52wh and is up 57% ytd.
Looking forward, the first two of the Magnificent 7 report CQ3 earnings next week on Wednesday.
For $META, while I see a beat and raise quarter, the stock is probably going to react to initial expense and capex guidance for 2027 coming in high, especially given the strong recent stock performance. The costs needed to support their hit Agentic product Muse and their recently released frontier LLM models, is likely to occur before their monetization.
For $TSLA, the videos of their new “flying” Roadster were mind blowing. This is just a reminder why engineering god Elon gets mind blowing valuations for his companies. I also believe the Roadster is a physical example of why $SPCX (which also reports next week) buying Tesla makes sense.
In summary, the recent correction made sense for reconciling some of the discrepancies between the bond market and equity markets. But I believe there is still a lot of infrastructure growth ahead to support the proliferation of personal Agents. As a result, I think it makes sense to invest some of the excess cash levels that I have been recommending.
The SOX is now down 8 days in a row for a loss of 15.7% through Friday. The last time the index fell for 8 or more consecutive trading days ended on Friday October 10th 2008 for a loss of 19.8%, during the Global Financial Crisis. It then bounced for just one day the following Monday for 9.7% before continuing to much lower levels. The AI trade may be having some funding concerns today but it is not as bad as during the GFC.
All the best in the week ahead.
Show more
Diabetes rates (age-standardised prevalence, adults 20–79):
🇵🇰 Pakistan: 31.4%
🇰🇼 Kuwait: 25.6%
🇶🇦 Qatar: 24.6%
🇪🇬 Egypt: 22.4%
🇲🇾 Malaysia: 21.1%
🇸🇦 Saudi Arabia: 23.1%
🇲🇽 Mexico: 16.4%
🇹🇷 Turkey: 16.5%
🇧🇩 Bangladesh: 13.2%
🇱🇰 Sri Lanka: 10.2%
🇿🇦 South Africa: 7.2%
🇮🇶 Iraq: 13.4%
🇺🇸 United States: 13.7%
🇮🇩 Indonesia: 11.3%
🇨🇳 China: 11.9%
🇪🇸 Spain: 9.7%
🇹🇭 Thailand: 10.2%
🇮🇳 India: 10.5%
🇮🇷 Iran: 9.0%
🇵🇹 Portugal: 10.5%
🇧🇷 Brazil: 10.6%
🇳🇵 Nepal: 7.7%
🇰🇵 North Korea: 9.9%
🇨🇦 Canada: 7.7%
🇵🇭 Philippines: 7.5%
🇰🇷 South Korea: 9.6%
🇯🇵 Japan: 8.1%
🇦🇺 Australia: 7.4%
🇮🇹 Italy: 7.7%
🇬🇧 United Kingdom: 7.4%
🇳🇿 New Zealand: 6.7%
🇻🇳 Vietnam: 6.4%
🇷🇺 Russia: 5.9%
🇦🇷 Argentina: 14.0%
🇫🇷 France: 6.5%
🇪🇹 Ethiopia: 4.4%
🇰🇪 Kenya: 3.1%
🇳🇬 Nigeria: 3.0%
🇳🇴 Norway: 4.8%
🇧🇪 Belgium: 5.9%
🇮🇪 Ireland: 3.6%
🌍 World: 11.1%
Note: Age-standardised prevalence of type 1 and type 2 diabetes among adults aged 20–79 years. Estimates include diagnosed and undiagnosed cases.
Source: International Diabetes Federation, Diabetes Atlas, 11th Edition (2025), estimates for 2024.
Show more
Average number of sexual partners:
🇹🇷 Turkey: 14.5
🇦🇺 Australia: 13.3
🇳🇿 New Zealand: 13.2
🇮🇸 Iceland: 13
🇿🇦 South Africa: 12.5
🇫🇮 Finland: 12.4
🇳🇴 Norway: 12.1
🇮🇹 Italy: 11.8
🇸🇪 Sweden: 11.8
🇨🇭 Switzerland: 11.1
🇮🇪 Ireland: 11.1
🇺🇸 USA: 10.7
🇨🇦 Canada: 10.7
🇬🇷 Greece: 10.6
🇯🇵 Japan: 10.2
🇬🇧 UK: 9.8
🇦🇹 Austria: 9.7
🇩🇰 Denmark: 9.3
🇧🇬 Bulgaria: 9.1
🇨🇿 Czechia: 9
🇧🇷 Brazil: 9
🇷🇺 Russia: 9
🇲🇽 Mexico: 9
🇫🇷 France: 8.1
🇭🇷 Croatia: 7.5
🇳🇱 Netherlands: 7
🇵🇹 Portugal: 7
🇭🇺 Hungary: 6.6
🇪🇸 Spain: 6.1
🇵🇱 Poland: 6
🇲🇾 Malaysia: 5.8
🇩🇪 Germany: 5.8
🇸🇰 Slovakia: 5.4
🇨🇳 China: 3.1
🇮🇳 India: 3
Source: World Population Review
Show more
Average number of sexual partners:
🇹🇷 Turkey: 14.5
🇦🇺 Australia: 13.3
🇳🇿 New Zealand: 13.2
🇮🇸 Iceland: 13
🇿🇦 South Africa: 12.5
🇫🇮 Finland: 12.4
🇳🇴 Norway: 12.1
🇮🇹 Italy: 11.8
🇸🇪 Sweden: 11.8
🇨🇭 Switzerland: 11.1
🇮🇪 Ireland: 11.1
🇺🇸 USA: 10.7
🇨🇦 Canada: 10.7
🇬🇷 Greece: 10.6
🇯🇵 Japan: 10.2
🇬🇧 UK: 9.8
🇦🇹 Austria: 9.7
🇩🇰 Denmark: 9.3
🇧🇬 Bulgaria: 9.1
🇨🇿 Czechia: 9
🇧🇷 Brazil: 9
🇷🇺 Russia: 9
🇲🇽 Mexico: 9
🇫🇷 France: 8.1
🇭🇷 Croatia: 7.5
🇳🇱 Netherlands: 7
🇵🇹 Portugal: 7
🇭🇺 Hungary: 6.6
🇪🇸 Spain: 6.1
🇵🇱 Poland: 6
🇲🇾 Malaysia: 5.8
🇩🇪 Germany: 5.8
🇸🇰 Slovakia: 5.4
🇨🇳 China: 3.1
🇮🇳 India: 3
Sources:
1. Key Statistics from the National Survey of Family Growth - CDC
2. Male Milestones: Men in Numbers - Manual
3. What’s the Average Person’s Number of Sexual Partners? - Healthline
4. Average number of sexual partners: By Age, Gender, and Country – Promiscuity Statistics - BedBible
Show more

The US manufacturing recovery is accelerating:
ISM Manufacturing PMI rose +2.3 points in July, to 55.6, the highest since May 2022.
This marks the 7th consecutive monthly expansion.
Since December 2025, the index has surged +7.7 points, the biggest increase since the 2020 pandemic recovery.
This comes as new orders rose +0.7 points, to 56.7, the 3rd-highest since February 2022, pointing to further strength ahead.
At the same time, the employment index jumped +3.1 points, to 52.8, the highest since August 2022, marking the first monthly expansion since January 2025.
Meanwhile, prices paid fell -1.9 points, to 71.1, the lowest since February, posting the 3rd consecutive monthly decline by a total of -13.5 points.
Manufacturing activity is gaining momentum.
Show more


KEYCORP $KEY Q3’26 EARNINGS HIGHLIGHTS
🔹 Adj. Revenue: $2.05B (Est. $2.05B) 🟡; +8% YoY
🔹 Adj. EPS: $0.51 (Est. $0.47) 🟢; +24% YoY
🔹 Net Interest Margin: 2.95%; +20 bps YoY
Segment Revenue:
🔹 Consumer Bank: $1.05B; +5.9% YoY
🔹 Commercial Bank: $1.20B; +7.7% YoY
Other Q3 Metrics:
🔹 Net Interest Income (TE): $1.31B; +9.6% YoY
🔹 Noninterest Income: $744M; +6.0% YoY
🔹 Investment Banking Fees: $214M; +16.3% YoY
🔹 Net Charge-offs: 0.32%; -10 bps YoY
🔹 CET1 Ratio: 11.1%; -70 bps YoY
🔹 Return on TCE: 15.11%; +260 bps YoY
🔹 Assets Under Management: $74.5B; +9.7% YoY
Capital Return:
🔹 Buybacks: $320M
🔹 Dividend: $0.205/share
Comments:
🔸 “These results reinforce our confidence in achieving and sustaining a return on tangible common equity of 15%+ by the end of 2027.”
Show more
