Kyle Reidhead | Milk Road
@KyleReidhead
- Analyst & CEO at @milkroaddaily @milkroadai
- Helping everyday investors catch technological trends early
- Check out my real-time portfolio below
2K Following 25.5K Followers
“AI token usage is going 500x from here” says @Jason
Anyone arguing that AI usage has peaked or compute demand is maxed out is completely lost and obviously doesn’t use the technology
We’re still at something like 2% of people in corporate America using AI today AND both OpenAI and Anthropic haven’t even launched agents at scale yet
We have only touched the surface of what’s possible with AI and the usage will not just grow (linear) it will ACCELERATE (exponential) from here
I feel like this is hard for people to wrap their heads around but if you want to understand where this market is going, you need to understand this trend.
It’s not stopping, it’s getting much bigger, and the mid-terms, rates or anything else will not stop this
It doenst mean the market goes up in a straight line, but as an investor don’t get lost in the noise. This is the biggest technological change in our lifetime
Think MUCH MUCH BIGGER
Show more

My estimate is SpaceX spends around $470B in the next 5 quarters… if he’s to get to 13GW
Elon just stepped in and said their capex efficiency is underestimated
My estimate is based on $30b/GW and then $45B with Vera Rubin’s
Not sure how Elon plans to get this cheaper outside of casting his own turbine blades… but looking forward to the next earnings call to learn more
If they can build 1GW for under $30B in 60-90days and immediately lease it for $50-$60B/year, the numbers here are insane
Show more

Nobody is better positioned to dominate AI right now than SpaceX (+Tesla)
For 2 reasons:
1. They're about to have the most compute in the world
2. They have multiple products to monetize their compute (hyperscalers don't even have this)
Sure, they can lease 1GW/$50B+ or they can route it to Grok/GrokBot and generate $100B+/year like the frontier models are experiencing (they already have 800k+ paying GrokBot users as of 2 weeks ago)
Elon can also route that compute to FSD, Robotaxis and eventually humanoids at Tesla, all of which will require significant amounts of training and inference compute as they scale up into the millions (FSD already close to 2 million users)
This is the big reason why Tesla needs to merge with SpaceX, it needs access to loads of compute as its products scale. Rather than rent it from SpaceX if they merge than they simply receive it at cost and have the ability to switch that compute from Tesla products back to short-term leases if needed
So effectively, Elon is building 1GW of compute for around $30B ($45B with Vera Rubins) and immediately able to lease it for $50B/year, plug it into Grok for $100B/year or use it for his fleet of autonomous robots
Oh, and this doesn't even start to consider the fact that the bulk of the worlds compute will end up coming from Space, and SpaceX has about a 10 year lead on the space market, in terms of cost effectiveness and load size with Starship
This will only push their position/moat even further ahead than it is today. I just dont see how SpaceX doesn't become the worlds most valueable company in the next few years
I still believe this stock is significantly undervalued and will continue to buy on pullbacks. I originally got our Milk Road PRO members in $SPCX at $115. If you want to see how I'm playing this market and check out my real-time portfolio you can do so here:
Show more

Wow! Binance just plugged a $6.34B hole in 2 days
BEARISH that crypto hacks have reached this level
BULLISH that crypto enables its companies to be SO PROFITBLE that they can fill $6.34B in 2 days on a weekend
0% chance any tradfi company can do that this fast
Show more
Through all the fears around Anthropic and OpenAI
It's pretty clear they will both hit $100B ARR each by the end of this year
That's a 10x by Anthropic and 5x by OpenAI in 1 year!
I'm sorry doomers but the internet companies never had this type of growth at the application layer in the late 90s
Sure, the infra stocks did well, similar to the infra stocks this time around with AI. But the difference here is that the application layer is printing money too.
Anthropics revenue jumped from $11.6B in Q2 to ~$16.8B in Q3, and thats during a slow September before the new models launched. October has been a very big month for token usage so we should expect $20B+ for Q4
And ever since OpenAI launched Codex and Astra their revenue have been on an absolute tear as well
But we're going to close out this year with $200B ARR from just 2 companies, in addition to the revenues coming from GrokBut, Muse, and more
To compare today to the .com bubble makes 0 sense
That makes has their panties in a knot anyway though and continues to sell off. I think there will be a violent v-shaped recovery soon when everyone realizes that the AI revenue is there to support the build out
I dont know exactly when it will happen, but it will happen
Show more

Why is the stock market getting NUKED right now?
Google -12.6%, Amazon -7%, Intel -25%, Nasdaq futures down 2%+... and it's happening after these companies posted some of the best cloud growth we've EVER seen
Here's what you need to know as an investor:
1. Google missed on revenue and EPS, search growth slowed to 12%, and free cash flow came in at NEGATIVE $9.07B after $51.4B of capex in a single quarter. The stock had its worst day in 20+ years and lost about $500B in value
2. Amazon piled on last night. AWS grew 39% (fastest in nearly 5 years) and Amazon posted its highest operating margin ever... but trailing 12-month free cash flow went to NEGATIVE $42.4B, from +$14.8B a year ago. And it signaled capex goes UP again next year
3. Intel finished the job. Weak Q4 guide, a PC slump, and a warning that it'll burn cash this year. Stock -25% premarket, dragging every chip name down with it.
One thing to note from all of this:
Nobody is worried about AI DEMAND. Demand is the one thing every company confirmed. Google Cloud more than doubled, Azure grew 48%, AWS is accelerating and still can't build capacity fast enough
So to be clear, demand is NOT the issue. Any bear who's focused on demand should be muted, they are out to lunch
The fear right now is the BILL
The 4 big hyperscalers free cash flow was -$26B combined. 3 of the 4 are now spending more than their businesses bring in
So they're borrowing more and more to fill that gap. Amazon's long-term debt went from $66B to $173B in just 9 months
These companies used to be the biggest cash machines on earth, buying back their own stock. Now they're issuing bonds to keep building. THAT'S the shift the market is repricing and struggling to wrap their head around... even though FCF is expected to go positive by the end of next year, and significantly higher into 2028
But here's the ironic part. Every dollar of that capex is REVENUE for somebody else: the chip, memory and power companies building this stuff out. Yet $MU is still down ~5% this morning. The market is selling the spenders AND the companies getting paid... it makes no sense!
I'm seeing people on X call this the AI bubble popping. Once again, I don't see it. Bubbles pop when demand dries up. Here demand is accelerating and these companies are spending MORE because they can't build fast enough. What's being repriced is how long investors are willing to wait for the cash
I continue to believe these dips are for buying and we go much higher as the market realizes that this negative fcf is only short-term and the revenue is showing up in many different places from AI
This is not a bubble, this is one of the greatest investing opportunities of our lifetime and the market continues to give us gifts at these prices. Take a look at what dips I'm buying and what my real-time portfolio looks like here:
Don't forget to give me a follow @kylereidhead for more insights on AI and markets
Show more

Chart number 4,875 that tells you we’re not in an AI bubble
This doesn’t happen if companies are spending less on AI or aren’t seeing ROI (or a path to ROI) on their AI spend
The demand for compute (aka intelligence) is infinite, the market just doesn’t know it yet
Show more

There will be TWO FIRSTS from the $SPCX Q3 earnings today:
1. SpaceX will print its first profitable quarter ever
2. >50% of SpaceX revenue will not come from Space, but instead AI
While the space & connectivity business is an incredible business growing very fast, it pales in comparison to an AI compute business which will almost 3x QoQ
My guess is they will see both a huge jump in revenue from AI compute, as they are now renting near $60m/MW/year, in addition to revenue from the AI labs (Grok/Cursor/xAI), with the launch of GrokBot and newer frontier level models with Grok
SpaceX is now an AI company with a rocket launch and connectivity business on the side, and this will become even more apparent in the quarters ahead
Show more

The most underrated part of SpaceX's business is that its data centers pay for themselves in MONTHS, not years
SpaceX is currently building them (pre Vera Rubin) for about $28M-$32M per MW
They can lease that compute on the spot market for $45M-$50M/MW every year. In the most recent deals, Deutsche Bank estimates SpaceX is leasing compute for $60M/MW!
Now these are the numbers if SpaceX rents out that compute. There's also a growing need for SpaceX to us that compute within their own business for Grok and GrokBot
In this scenario, SemiAnalysis estimates that 1GW of compute being used to sell frontier model tokens is worth about $100B/year, 2x the amount of renting it out
Now of course, SpaceX doesn't have many GWs of compute in demand for their AI model (yet), so they can't eat up all of that supply on their own. But, if SpaceX and Tesla merge, then that compute can be used for the compute needs of Robotaxis and Humanoids in the future too, which will also have a high ticket rev return as these networks grow
Effectively, SpaceX is building a compute business with the optionality to rent it out for $50M/MW+ or use it internally for upwards of $100m/MW
And they expect to hit 2.6GW of compute by the end of 2026 and 10GW by EOY 2027. The revenue implications of this for SpaceX are absolutely massive
SpaceX will be one of the fastet growing companies by revenue in 2027 if they can actaully reach those numbers of compute
Great episode on $SPCX from @kukulabanze on the @MilkRoadStocks podcast yesterday
Show more

This morning I went discount shopping and initiated a position in $NBIS at $164 and bought more $SPCX at $141
I also sold my $AAPL at ATHs to fund these buys, so I still maintain my cash position
I realize there are risks w/ higher rates/inflation & Anthropic financials
But I continue to believe that the demand for compute is much much higher than the market realizes. I also believe that this compute remains scarce for years ahead, which means the pricing power of compute builders/owners remains strong
Regardless of the markets random ARR estimates of Anthropic or OpenAI, the secular demand to turn energy into intelligence is not stopping. Whether this comes from frontier model providers, agent harnesses, open models or elsewhere, we will use more AI tomorrow than today
And the more companies use AI, the more efficient and profitable they will become (we are seeing it in so many companies already). It will not be in a straight line but it will continue to be up and to the right... I know this for sure
This is why I am continuing to build positions in those who are capable of turning energy into intelligence
By the way, you can track all of these moves in real-time and see what else I hold in my portfolio inside Milk Road PRO here:
Nebius is the one neocloud that has a strong balance sheet and could whether a big storm. They have $8B of cash and could even acquire some of the many neoclouds who will likely fail at discounted prices
Even more so on this is SpaceX, with more than $100B in capital sitting on their balance sheet, they will imo be the biggest buyer of compute if things fall apart. Their numbers already look good at current build prices, if they were to get discount prices from distressed companies, that would be a bonus
Higher rates makes financing compute a little more difficult, it doesn't make it impossible, not even close. which means compute businesses who manage their capital well can continue to flourish during these times. I think Nebius and SpaceX will be those two companies
Maybe we go lower, maybe we don't. I dont know in the short-term, but in the long-term I think both of these companies are going much higher
Show more

Elon Musk replied to my post about $SPCX competition hurting the valuations of Coreweave & Nebius
I explained how SpaceX is moving so fast that they're taking scarce resources and capital that Neoclouds need to succeed
My guess is for Elon to reach 10GW by EOY'27 its not just from BUILDING compute, but from BUYING compute from distressed neoclouds
Maybe this is why he replied "yikes" to @chamath's post about Coreweave yesterday too. Elon is on a mission to acquire as much compute as possible, one way or another
As I've said many times, access to compute is the biggest moat for any company right now and not only is SpaceX going after as much as possible on earth, they are moving towards building compute in Space too
Another product that SpaceX has a clear moat in, both in the transportation of GPUs into space, but also in the ability to beam it down back to earth via Starlink
I explained this in the post that Elon replied "interesting" to
I don't know exactly what part of these posts were specifically interesting to Elon, but it's clear that Elon is building to become the largest owner of compute in the world
His plan is to either rent that out to the many enterprises who need access to compute (remember, compute = intelligence and intelligence = labour) with the optionality to use it for Tesla's Robotaxis and Humanoid Robots or SpaceX's Grok as the demand is needed
His plan is to acquire as much compute as possible and then have the optionality to rent it or use it for the products his companies build
What Elon is building with SpaceX and Tesla is by far the most ambitious endeavour in the world and I think these two companies (soon to be combined imo) will become the largest company in the world, by a large amount as this all plays out
Both $TSLA and $SPCX remain core assets in my Milk Road PRO portfolio. Yes, I know every analyst will tell you they are both way overvalued, but I think they are wrong.
In a world of AI, almost no one has a true moat. However, Tesla and SpaceX both have multi-year leads across the industries they compete in (or are inventing), they have the best engineers in the world and a leader that's relentless and always multiple steps ahead of others
I think both of these companies are a must own in any portfolio. If you'd like to see my entire portfolio in real-time, you can track it here:
Show more

So here’s where things stand…
Anthropic hit $16.8B in Q3, yet its spend via ramp has jumped significantly in October
At the same time, OpenAI growing considerably fast in Q3, close to matching Anthropic
Plus, we have SpaceX and Google showing up
Not to mention, agent revenues like GrokBot, Muse or Dots won’t show up here as that usage is in the companies own harness
So my best guess is Anthopic sits above $70B ARR today, OpenAI is likely $60B-$70B and xAI, Muse and others are around $10B ARR
So let’s say we’re close to $140B-$145B with 2.5 months left in the year
All of this while agent use cases are gaining traction and accelerating within the last month.. a big reason why revenues across all the AI companies are growing again
Hard to see us not hit $200B ARR by the end of the year across Anthropic, OpenAI, SpaceX and Meta
Meanwhile, compute companies are down 10-15% on the day
Seem extremely irrational…
I’d say the market is giving us another incredible buying opportunity here
Show more

Raymond James reiterates Strong Buy on $SPCX with a Street-high $800 price target!
The reason is SpaceX's FAA filing for up to 456 Starship launches and 912 landings a year at Boca Chica
At 60 V3 Starlink satellites per Starship, phase one's 100 flights a year means about 6,000 satellites. The full 456 flights means about 27,400
At 100 tons of payload and 100 kW per ton, Raymond James says 100 flights could deploy about 1 GW of orbital AI compute every year
That's before counting the Florida pads (44 a year at LC-39A, 76 at SLC-37) and Louisiana's planned $100 billion 10-pad spaceport
And Elon confirmed the upper stage catch is coming on the next flight, about 4-6 weeks out
Starlink and Orbital Compute are the future products of SpaceX and the competition is many years behind these products (and the ability to deploy them)
SpaceX is building the strongest moats in the world and that's why the stock deserves to be much higher than it is today
Show more


$SPCX isn't just building compute faster than every other neocloud
It has something none of them have: OPTIONALITY on every GPU it deploys
Every GW SpaceX brings online has two paths to revenue:
1. use it for Grok / xAI and capture the frontier model economics themselves, which generates more revenue than renting it out (Semianalysis estimates around $100B/GW)
2. rent it out to everyone else, at a premium
The reason SpaceX can rent out their compute at a premium is twofold:
1. Speed. SpaceX builds faster than anyone on earth, so they can get compute into customers' hands faster than any competitor. AI labs that need compute NOW pay up for that
2. The backstop. SpaceX can sign short-term contracts at higher prices because if a customer backs out, that compute simply goes to their own AI models. No empty racks, no panic
CoreWeave and Nebius can't take that risk, so they lock in most long-term deals at lower rents and fund the buildout with debt
Which brings us to funding, which is where the gap between these companies gets even wider
SpaceX doesn't have to fund the buildout (or the interest costs) from compute revenue alone. Starlink and launch cash flows can carry part of it. CoreWeave is paying 15% on unsecured bonds right now while SpaceX has diversified revenue streams across the whole company (and the best capital raiser alive running it)
And the part almost nobody is pricing in: as compute moves to space in the next few years, SpaceX owns the cheapest path to win there too. The rockets that bring the compute up AND the connectivity that beams it back down
That's why the chart above looks the way it does. Bloomberg Intelligence models SpaceX's AI ROIC going from negative 4% in 2026 to ~25% by 2030, above AWS and Google Cloud, while the pure neoclouds stay stuck in single digits
No one is better positioned to dominate the compute business in the coming years than SpaceX
This is why I still believe SpaceX is undervalued and why I've made it a core holding in my Milk Road PRO portfolio. You can see my entire real-time portfolio here:
Show more

As I've been saying...
DeFi + Tokenized stocks is the next big catalyst for crypto
there are WAY more stock investors than crypto investors
what DeFi is going to unlock is the ability to permissionlessly DO THINGS with your favourite assets
- lend and borrow against stocks
- add perps to stocks
- become a market maker for your fav stocks on AMMs
and the list goes on and on
If you want to bring stock investors onchain, we needed to first get their favourite assets onchain and then unlock new use cases and incentives
Thats exactly what @aave is doing here with Coinbase stocks on @base
Bullish DeFi
Show more
Is SpaceX competition hurting the valuation / credit risk of Neoclouds?
$CRWV and $NBIS down 10%+ today, while $SPCX down just 2% (and UP on the month)
The obvious trigger is credit risk, with CoreWeave's unsecured bonds yielding 15%
But in the last week, Elon also confirmed that SpaceX will reach 2GW by November and potentially 2.6 GW by EOY. That's .6GW ahead of schedule and quickly becoming much bigger than Coreweave and Nebius
Almost no one building compute is doing it ahead of schedule, but SpaceX is proving to be superior here on speed and is expecting close to 10GW by 2027 (And significantly more in years ahead, especially as we move to compute in Space)
At the same time, Elon also mentioned earlier this week about the difficulty in executing this build out (said even SpaceX engineers are finding it hard) but also in the ability for companies to raise capital... the issue Coreweave is having now.
But we know SpaceX and Elon has no issues in raising capital (and generating revenue from other sources too). Raising capital is what Elon excels at over anyone
So I wonder if the market is starting to see that SpaceX is becoming a very big competitor to these neoclouds, taking demand sure... though I think there is plenty of demand to go around.. but more so taking resources and capital that other neoclouds need to scale
SpaceX also has optionality to either rent out the compute or use it for xAI / Grok, which lowers risk even further to fund their compute buildout. It's also why SpaceX can charge a premium on their compute vs the other neoclouds, lowering risk even further
I'm not saying SpaceX is the full reason for Coreweaves issues, but you gotta think this evolving competitive landscape of Elon entering the ring has to have something to do with it
Even with this said, I'm still bullish on neoclouds as I think the demand remains endless, but I think SpaceX becomes the dominate neocloud by next year
Show more

Everyone's worried $NVDA is "losing share" to custom chips
They're missing the point. UBS has Nvidia going from 7.5 GW of AI rack capacity in 2025 to 50.5 GW in 2030
That's ~7x in 5 years
Yes, Nvidia's share shrinks on this chart. It goes from ~65% of all AI racks in 2025 to ~48% by 2030, as custom ASICs (Google TPUs, Amazon Trainium) grow from ~4 GW to 45 GW
But share is the wrong number to watch. The total market goes from 11.5 GW to 104.5 GW, roughly 9x
A slightly smaller slice of a pie that's 9x bigger is still a monster. Nvidia adds ~11 GW in 2027 ALONE, which is about the size of the entire AI rack market in 2025
And the competitors growing doesn't mean they're catching up on the product
SemiAnalysis just benchmarked Vera Rubin on agentic inference. On one test it delivered ~30x the throughput per dollar of AMD's MI355X, and even beat Nvidia's own GB300 by 1.4-3x at the speeds most providers actually serve models
Hyperscalers build ASICs to lower costs on their own workloads. Everyone else (the labs, the neoclouds, sovereign AI, enterprises) still buys Nvidia because it's the best product you can get
And here's the kicker: even 104 GW won't be enough
SpaceX alone is targeting 10-20 GW of compute by the end of 2027. That's equal to 20-40% of all the AI racks UBS expects the world to deploy in 2027, for one company. Now add OpenAI, Anthropic, Meta, Google, Microsoft and every agent we haven't even launched yet
Demand isn't the constraint here, supply is
$NVDA remains a core holding inside my Milk Road PRO portfolio. If you want to see what else I hold, you can check out my real-time portfolio here:
Don't forget to give me a follow @kylereidhead for more insights on AI and markets
Show more

the answer is: because its a worldwide bond crisis
Bitcoin was built to give you an out when the tradfi system breaks
So every time there are cracks in the system, whether it be bank failures or the bond market breaking
Bitcoin sniffs out that the only answer is to manipulate the currency through debasement (in one way or another)
Bad news is good news for Bitcoin long-term
Show more
This is the most insane thing from Open AI Dev Day
ChatGPT just hit 1.2 billion weekly users and 2.5M+ businesses are using its products!
They are already generating $70B ARR off this user base and are expanding their ads business with expectations of $2.5B ARR by EOY
How can you be bearish on this company?
They just grew their revenues almost 75% in the last 1.5 months, adding $30B in ARR since early August
I think OpenAI is going to be just fine and the concerns around their business struggling or defaulting is just nonsense
The revenues for AI labs continue to show up, and if they can start to generate revenue from ads or txn fees too, then I think the labs will become unstoppable companies
The only AI lab risk left is Anthropic, but seeing as they are moving ahead with IPO my guess is the numbers aren't as bad as the market is making it out to be
The aI infra trade is going higher, that's why I see from these numbers OpenAI just released
By the way, if you want to see how I'm allocating to this market, you can check out my real-time portfolio at the link in my bio
Good luck out there!
Show more

These numbers are insane!
A single Starship launch with Starlink satellites will soon add >$1 BILLION of ARR to $SPCX
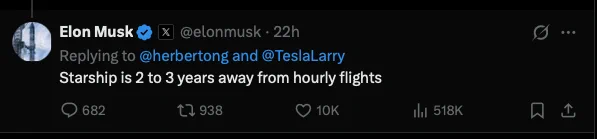
...And Elon expects them to hit hourly launches in 2-3 years!
Here's the math:
Starship will carry 60 V3 Starlink satellites per flight, each with roughly 1 Tbps of downlink
That's 60 Tbps of new capacity per launch, more than 20x what a Falcon 9 delivers today
Starlink is currently doing ~$17B in annualized revenue on ~800 Tbps of capacity, which works out to roughly $21M of revenue per Tbps
60 Tbps x $21M = ~$1.3B of annualized revenue capacity from ONE launch (wow).
And here's the part nobody is pricing in:
Elon said yesterday he expects DAILY Starship launches in 2027 and hourly launches within 2 to 3 years
Yes, revenue per bit falls as capacity scales, but Elon's own math says comms revenue can still exceed $200B/year even if price per gigabit drops 10x
I'm not sure anyone is ready for the size of the revenues SpaceX is about to generate, especially if you consider that these revenues have nothing to do with the 60+GW of compute they expect to bring online in the next 5 years!
Of course, $SPCX is an asset I hold in my Milk Road PRO portfolio, where you can track 5 analysts' real-time portfolios and research with live trade notifications
It's just $1 to try it out (insane price just to check it out), learn more here:
Don't forget to give me a follow @kylereidhead for more insights on AI and markets
Show more