Search results for 260620アメージングカップ
260620アメージングカップ community
One keyword maps to one global community path.
People
Not Found
Tweets including 260620アメージングカップ

BREAKING: US stock market futures fall as diesel prices hit a record high and Middle East tensions mount:
1. S&P 500: -0.6%
2. Nasdaq 100: -1.1%
3. Dow Jones: -0.4%
4. WTI Crude: +3.0%
5. Brent: +3.0%
6. Natural Gas: +2.0%
Today marks day number 197 of the Iran War.
Show more
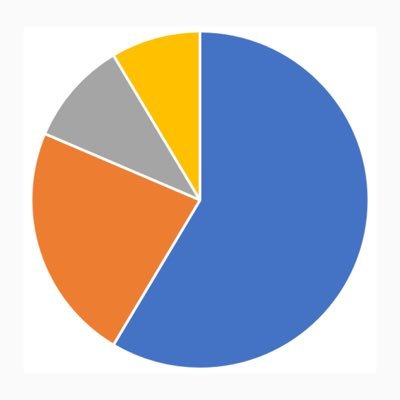
☕ Countries that drink the most coffee
Share of global coffee consumption, 2025/26:
1. 🇺🇸 United States: 14.7%
2. 🇧🇷 Brazil: 12.8%
3. 🇩🇪 Germany: 6.4%
4. 🇯🇵 Japan: 3.8%
5. 🇵🇭 Philippines: 3.8%
6. 🇨🇳 China: 3.7%
7. 🇨🇦 Canada: 2.9%
8. 🇫🇷 France: 2.9%
9. 🇻🇳 Vietnam: 2.8%
10. 🇮🇩 Indonesia: 2.8%
11. 🇷🇺 Russia: 2.6%
12. 🇬🇧 United Kingdom: 2.6%
13. 🇪🇹 Ethiopia: 2.6%
14. 🇮🇹 Italy: 2.4%
15. 🇪🇸 Spain: 2.0%
16. 🇰🇷 South Korea: 1.8%
17. 🇲🇽 Mexico: 1.8%
18. 🇵🇱 Poland: 1.6%
19. 🇦🇺 Australia: 1.5%
20. 🇨🇴 Colombia: 1.3%
21. 🇳🇱 Netherlands: 1.2%
22. 🇩🇿 Algeria: 1.2%
23. 🇸🇪 Sweden: 1.1%
24. 🇹🇷 Türkiye: 1.0%
25. 🇮🇳 India: 0.9%
26. 🇸🇦 Saudi Arabia: 0.8%
27. 🇷🇴 Romania: 0.7%
28. 🇨🇭 Switzerland: 0.7%
29. 🇪🇬 Egypt: 0.7%
30. 🇦🇹 Austria: 0.6%
The world drinks 173.5 million 60-kg bags of coffee a year. Europe accounts for 32%, Asia-Pacific 23% and North America 21%.
Green bean equivalent consumption, 2025/26 marketing year (October–September in most countries). These are country totals, not per person.
Source: USDA Foreign Agricultural Service, European Coffee Federation
Show more

CHARLES RIVER $CRL Q3’26 EARNINGS HIGHLIGHTS
🔹 Revenue: $982.7M (Est. $959M) 🟢; -2.2% YoY
🔹 Adj. EPS: $3.09 (Est. $2.97) 🟢; +27.2% YoY
🔹 Non-GAAP Oper Income: $225.8M (Est. $217M) 🟢
Raises FY26 Guide:
🔹 Reported Revenue Growth: -2.0% to -1.5% (Est. -2.5%) 🟢
🔹 Adj. EPS: $11.35-$11.55 (Est. $11.38) 🟡
🔹 Organic Revenue Growth: At least +1.5%
Segment Net Revenue:
🔹 DSA: $596.3M; -0.7% YoY; +5.9% organic
🔹 Manufacturing: $178.9M; -6.2% YoY; +7.4% organic
🔹 RMS: $207.5M; -2.8% YoY; -0.6% organic
Other Q3 Metrics:
🔹 Organic Revenue Growth: +4.7%
🔹 Non-GAAP Operating Margin: 23.0%; +330 bps YoY
Key Updates:
🔹 Tax Reserve Reversal: $245.6M benefit; $5.06 per share
Comments:
🔸 “Revenue and earnings per share outperformed our prior expectations, DSA net bookings and proposals continued to show robust, year-over-year increases”
Show more


HERE IS HOW THE MARKET CLOSED TODAY
Five of eleven sectors finished green. Technology was the worst at -1.1%, Basic Materials -1.8% and Real Estate -1.1% behind it.
Chips led the selling:
- Lam Research $LRCX -5.6%
- Intel $INTC -5.6%
- Micron $MU -4.7%
- Advanced Micro Devices $AMD -3.4%
- Nvidia $NVDA -2.4%
Software and hardware went with them. Oracle $ORCL -5.2%, Dell $DELL -5.4%, Hewlett Packard Enterprise $HPE -6.2%, Palantir $PLTR -2.2%.
Apple $AAPL +3.6% was the largest megacap gainer, the day after its iPhone event. Google $GOOGL +0.6% and Microsoft $MSFT +0.2% held up. Meta $META -1.4% and Tesla $TSLA -1.2% did not.
Defensives caught the rotation. Philip Morris $PM +2.2%, AbbVie $ABBV +1.6%, Uber $UBER +2.1%, Intuitive Surgical $ISRG +2.0%.
Consumer Defensive was the best sector at +0.3%.
Show more


Last wk, earnings had elements of all the AI issues I feared in my preview. $GOOGL – AI disintermediation fear for search and big FCF miss. $MSFT – neocloud partner pushing out capacity and 1st new fundraising bonds since 2017. $AMZN – AI growth miss in AWS and FCF miss.
Tech took a beating last week with Nasdaq -2.0% and Mag7 -2.4% but with S&P down only 0.6%. However, the nine non-tech related sub sectors (out of the eleven total) were strong and up 1.0-3.1%. As a result, the equal weighted S&P was up 0.8%. The above three names all declined last week with Google down 12.6%, Amazon -3.1% and Microsoft -0.5%. The historic 28.6% stock decline by $INTC on Friday (-24.4% for the week) did not help. This helped drive the SOX Index down 7.2% on Friday though the weekly decline was only 0.8%.
With all the hyperscalers now having reported, here are my current thoughts:
1) Microsoft has committed to staying FCF positive (with $18.6B in FCF in CQ3) and is the only name in this list that has committed to do so. M365 is likely to become the default option for enterprises that want AI in a safe environment through use of Co-Pilot.
2) Meta is using AI to improve the efficiency of their business as seen in their ad revenues compared to Google. Also Muse has been a hit with consumers for Agentic AI while they are appealing to enterprises with their strong open-weight models. An 18x CY27 PE for 28% revenue growth is appealing. Their major blemish is the future negative FCF expected with a $2.1B burn in Q3 driving them to raise ~$95B in equity financing following earnings results. S&P Global Ratings on cash flow concerns and AI spending revised their credit rating today from AA- stable to AA- negative.
3) Amazon despite missing buyside AWS expectations of ~42% y/y growth with 39% reported (official sellside consensus of 38%) expects 40% revenue growth for AWS in CY27 and CY28 despite being the largest public cloud vendor. Also their LTM FCF burn of $42.4B in Q3 vs $7.6B in June helped lead to a $80B supplier financing arrangement facility post-earnings. Also physical AI should benefit their e-commerce business. Both e-commerce and AWS were guided to be $1 trillion revenue businesses within the next 5-10 years.
4) Google’s new LLM model is back at the frontier with a low cost per token. However this miss in search revenues for the 2nd quarter in a row and first miss in both total revenues and EPS for the first time since late 2022 raises AI disintermediation fears. FCF burn of $9.1B was also more than expectations. But total search queries are at the highest levels in five years. As a result, as ad coverage and loads increase on their AI queries, these fears should pass much like in late 2025. Ultimately, I believe Google will be a winner in consumer AI through their distribution through Android phones.
As for Intel, I did not see this coming. On October 20th, $SMCI (purely enterprise related revenues) pre-announced 27% revenue upside along with a raise to gross margins guidance to 12-12.5% from 10.4%-10.8% for their CQ3. I am not a fan of SuperMicro to be clear. For the processor vendors, I thought upside in server revenues due to Agentic AI would offset the downside in their PC business due to memory related price increases lowering demand. $AMD, which is gaining share, reports earnings on Tuesday. This will help investors understand whether this is an Intel specific issue or industry issue. I would note that Microsoft’s guidance for their Windows OEM & Devices business was down ~35% y/y for December vs -22% in September and -7% in June.
Longer-term, I believe Intel will become a force in the foundry industry but in the near-term it may take some time for the valuation to reset lower due to their current microprocessor business.
Looking forward, $AAPL reports on Monday after the close. The stock has been a beneficiary of investors looking to avoid AI companies with huge FCF burns. However, I would be wary into earnings that are likely to provide lower than expected guidance for the December quarter from a combination of higher currency impact, margin compression from semiconductor price increases, iPhone unit pressure from higher ASPs, a slowdown in services revenues and less than expected high margin TAC revenue from Google. Ultimately, I believe Apple will be a winner in consumer AI through their distribution through iPhones. I also believe their new foldable phone will drive a large upgrade cycle in 2027. But in the near-term I believe it is prudent to remove Apple (up 27% ytd) from my Top5 Picks that I put out when 2026 started. As a reminder this is meant to be a buy and hold list for the entire year for those that do not have time to be managing things daily which is what I do. I believe Apple is likely to be a Top 5 Pick at the start of 2027.
We are now entering the seasonally strongest month of the year. Since 1957, which is the inception of the modern day S&P500, November is up +1.8% and tied for the best hit rate with April & December at up 71% of the time. This compares to an average return of 0.7% and hit rate of 61% for all months.
Surprisingly, the returns for November in mid-term election years is even better with an average of 2.6% and hit rate of 82%. This might have to do with the ytd annual return being lower going into the elections at -1.8% through October with a hit rate of 53% so there is a relief rally on the other side.
In summary, this earnings season has been more trick than treat for technology investors. Being more discerning and trading around positions has been the correct tactic. I think will continue to be the case. Let us hope November gives us something to be thankful for.
All the best in the week ahead.
Show more
CHOOSE YOUR FIGHTER
Warren Buffett vs Stanley Druckenmiller
Buffett stepped down as Charman of Berkshire Hathaway $BRK.B today. Druckenmiller has never had a losing year in more than 30 years.
Here are their full portfolios as of Q2 2026.
BERKSHIRE HATHAWAY
- Apple $AAPL: 22%
- American Express $AXP: 17%
- Google $GOOGL: about 12.6% across both share classes
- Coca-Cola $KO: 11%
- Bank of America $BAC: 9.2%
- Chevron $CVX: 4.7%
- Occidental $OXY: 4.3%
- Chubb $CB: 3.9%
- Moody's $MCO: 3.7%
- Kraft Heinz $KHC: 2.6%
- DaVita $DVA: 2.1%
- Delta $DAL: 1.8%
- SiriusXM $SIRI: 1.2%
- VeriSign $VRSN: 0.8%
- Kroger $KR: 0.7%
- Liberty Live $LLYVA: about 0.6% across both share classes
- Ally $ALLY: 0.4%
- Lennar $LEN: 0.4%
- New York Times $NYT: 0.4%
- Capital One $COF: 0.2%
- Louisiana-Pacific $LPX: 0.1%
- Nucor $NUE: 0.1%
- Macy's $M: 0.1%
- NVR $NVR
- Jefferies $JEF
- D.R. Horton $DHI
DUQUESNE FAMILY OFFICE
- Natera $NTRA: 17%
- Insmed $INSM: about 5.7% in shares and calls
- Taiwan Semi $TSM: 5.4%
- Brazil ETF $EWZ: about 5.1% in shares and calls
- Amazon $AMZN: about 4.6% in shares and calls
- STMicro $STM: 4.5%
- S&P 500 Equal Weight $RSP: about 3.7% in calls and shares
- Fox $FOXA: about 2.8% across both share classes
- YPF $REPYY: 2.7%
- CDW $CDW: about 2.7% in shares and calls
- BBB Foods $TBBB: 2.3%
- Google $GOOGL: 2.3%
- Seagate blockstack:native: 2.3%
- United Airlines $UAL: 2.1%
- Sea $SE: 2.0%
- NewAmsterdam Pharma $NAMS: 2.0%
- Russell 2000 ETF $IWM: 1.9% in calls
- Sandisk $SNDK: 1.5%
- Revolution Medicines $RVMD: 1.4%
- S&P 500 ETF: 1.3% in calls
- Bitdeer: 1.2%
- CRH: 1.1%
- Delta: 1.1%
- Tesla $TSLA: 1.0% in calls
- Fluor: 1.0%
- D.R. Horton: 0.9%
- Coupang: 0.9%
- AMD: 0.8%
- Palo Alto Networks: 0.8%
- Cleveland-Cliffs: 0.8%
- Hut 8: 0.7%
- Caris Life Sciences: 0.6%
- Argentina ETF: 0.6%
- Woodward: 0.5%
- Meta: 0.5% in calls
- Nuvation Bio: 0.5%
- Protagonist Therapeutics: 0.5%
- Roku: 0.5%
- Cavco: 0.5%
- ADMA Biologics: 0.4%
- Hyperliquid Strategies: 0.4%
- Rambus: 0.4%
- Rhythm Pharmaceuticals: 0.4%
- Champion Homes: 0.4%
- Daktronics: 0.4%
- PureCycle: 0.4%
- Southern Copper: 0.4%
- Linde: 0.4%
- Entegris: 0.4%
- Teva: 0.4%
- Unity: 0.4%
- Aeva: 0.4%
- Riot Platforms: 0.4%
- Qnity Electronics: 0.4%
- Equinix: 0.4%
- Lam Research: 0.4%
- Definium Therapeutics: 0.3%
- Belite Bio: 0.3%
- 10x Genomics: 0.3%
- Wabtec: 0.3%
- Eli Lilly: 0.3%
- Xenon Pharmaceuticals: 0.3%
- Olema Pharmaceuticals: 0.2%
- Repligen: 0.2%
- Rocket Companies: 0.2%
- Baidu: 0.2%
- Arm: 0.2%
- Carvana: 0.2%
- Reddit: 0.2%
- Alcoa: 0.2%
- Thermo Fisher: 0.2%
- Danaher: 0.2%
- F5: 0.2%
- Vista Energy: 0.2%
- Skeena Resources: 0.2%
- JBS: 0.1%
- Monte Rosa Therapeutics: 0.1%
- Relay Therapeutics: 0.1%
- DBV Technologies: 0.1%
- CCC Intelligent Solutions: 0.1%
- UWM Holdings: 0.1%
- Navitas Semiconductor: 0.1%
- Solstice Advanced Materials: 0.1%
- FTAI Aviation: 0.1%
- Beam Therapeutics: 0.1%
- Aurora Innovation: 0.1%
- IREN: 0.1%
- Grupo Financiero Galicia: 0.1%
- Wave Life Sciences: under 0.1%
Both own Google, Delta and D.R. Horton. Neither owns Nvidia $NVDA.
Show more

I’d like to share that I’ll be leaving Bandai Namco at the end of 2025.
With the TEKKEN series reaching its 30th anniversary—an important milestone for a project I’ve devoted much of my life to—I felt this was the most fitting moment to bring one chapter to a close.
My roots lie in the days when I supported small local tournaments in Japanese arcades and in small halls and community centers overseas.
I still remember carrying arcade cabinets by myself, encouraging people to “Please try TEKKEN,” and directly facing the players right in front of me.
The conversations and atmosphere we shared in those places became the core of who I am as a developer and game creator.
Even as the times changed, those experiences have remained at the center of my identity.
And even after the tournament scene grew much larger, many of you continued to treat me like an old friend—challenging me at venues, inviting me out for drinks at bars.
Those memories are also deeply precious to me.
In recent years, I experienced the loss of several close friends in my personal life, and in my professional life I witnessed the retirement or passing of many senior colleagues whom I deeply respect.
Those accumulated events made me reflect on the “time I have left as a creator.”
During that period, I sought advice from Ken Kutaragi—whom I respect as though he were another father—and received invaluable encouragement and guidance.
His words quietly supported me in making this decision.
Over the past four to five years, I’ve gradually handed over all of my responsibilities, as well as the stories and worldbuilding I oversaw, to the team, bringing me to the present day.
Looking back, I was fortunate to work on an extraordinary variety of projects—VR titles (such as Summer Lesson), Pokkén Tournament, the SoulCalibur series, and many others, both inside and outside the company.
Each project was full of new discoveries and learning, and every one of them became an irreplaceable experience for me.
To everyone who has supported me, to communities around the world, and to all the colleagues who have walked alongside me for so many years, I offer my deepest gratitude.
I’ll share more about my next steps at a later date.
Thank you very much for everything.
【Postscript】
Although I will be leaving the company at the end of 2025, Bandai Namco has asked me to appear at the TWT Finals at the end of January 2026, so I expect to attend as a guest.
For 30 years I kept saying, “I’ll do it someday,” and never once performed as a DJ at a tournament event.
So instead, I will be releasing—for the first and last time—a 60-minute TEKKEN DJ-style nonstop mix (DJ mix), personally edited by myself, together with this announcement.
Listening to it brings back many memories.
Thank you again, sincerely, for all these years.
‘TEKKEN: A 30-Year Journey – Harada’s Final Mix’ by Katsuhiro Harada 1 is on #SoundCloud#
December 8, 2025 - The Final Day of TEKKEN’s 30th Anniversary -
Katsuhiro Harada
[日本語版 (Japanese version)]
このたび、2025年末をもちまして、私はバンダイナムコを退職することにいたしました。
長く携わってきた『鉄拳』シリーズが30周年という大きな節目を迎え、ひとつの区切りとして最もふさわしい時期であると考えたためです。
私の原点は、日本のゲームセンターや、海外コミュニティの小さな講堂やコミュニティセンターで、まだ小規模なトーナメントをサポートしていた時代にあります。
アーケード筐体を自ら運び込み、「鉄拳もぜひ遊んでみてほしい」と声をかけながら、目の前の参加者と向き合った日々。
あの場で交わした言葉や空気が、私という開発者の核を形作りました。
時代が変化しても、あの経験が自分の中心にあります。
そしてトーナメントシーンが大きく成長した後も、皆さんは旧知の友人のように私に声をかけ、会場で対戦したり、バーで『一緒に飲もう』と誘ってくれました。
それらもまた、大切な思い出です。
ここ数年間、私生活においては友人達との死別があり、仕事においては、私が尊敬する多くの先輩方の引退や逝去に触れてきました。
そうした出来事の積み重ねが、私に『開発者として残された時間』について考える契機を与えました。
その過程で、私がもう一人の父親のように敬愛する久夛良木健さんにも相談し、貴重な助言と励ましのお言葉をいただきました。
この言葉もまた、今回の決断を静かに後押しするものとなりました。
そして、この4〜5年をかけて私の担ってきたすべての業務やストーリーや世界観、そして責務をチームに段階的に引き継ぎ、今日に至ります。
振り返れば、VR作品(サマーレッスンなど)や『ポッ拳』、ソウルキャリバーシリーズをはじめ、自社他社問わず数多くのプロジェクトに携わる機会に恵まれました。
いずれのプロジェクトも新しい発見と学びに満ち、かけがえのない経験となりました。
これまで支えてくださった皆様、世界中のコミュニティの皆様、そして長年ともに歩んできた仲間たちに深く感謝申し上げます。
次の歩みについては、改めて皆様にお伝えいたします。
これからも、どうぞよろしくお願いいたします。
+あとがき
2025年末をもって退職致しますが、2026年1月末のTWT FINALには顔を出してほしいと会社からお願いされていることもあり、FINALにはゲストとして顔を出すと思います。
これまで30年間『いつかやるよ』と言い続けてやってこなかったトーナメントイベントでのDJですが、その代わりとして“最初で最後のDJ風60分ノンストップ鉄拳ミックス(私による初編集DJ mix)”も、今回のポストに合わせて公開します。
‘TEKKEN: A 30-Year Journey – Harada’s Final Mix’ by Katsuhiro Harada 1 is on #SoundCloud#
様々な思い出が蘇ります。改めて皆さんありがとうございました。
2025年12月8日 - 鉄拳30周年最終日 -
Katsuhiro Harada
Show more

rippled 2.6.0 has been released!
XRPK infrastructure is already running on it, with 271 nodes (25% of the network) upgraded.
This update has no amendments to vote on.
Huge thanks to all contributors, and we urge all node operators to upgrade.
Source: @xrpscan @bithomp
#XRPLedger# #XRPCommunity# #XRP#
Show more


Spain Industrial Production (M/M) Jul: 0.6% (est 0.2%; prev -0.7%)
- Industrial Output SA (Y/Y): 2.3% (prev 1.1%)
- Industrial Output NSA (Y/Y): 2.6% (prev 3.8%)
UK Industrial Production (M/M) Jul: 0.2% (est -0.2%; prev -0.2%)
- Industrial Production (Y/Y): 0.6% (est 0.2%; prev -0.2%)
- Manufacturing Production (M/M): 0.9% (est 0.2%; prev -0.5%)
- Manufacturing Production (Y/Y): 2.6% (est 2.1%; prev 0.5%)
Show more