Brad Setser
@Brad_Setser
CFR senior fellow. Views are my own. Writes on sovereign debt, trade, fx reserves and capital flows.
1.1K Following 160.1K Followers
Incidentally, the EU won't have much trouble proving a surge in imports of organic chemicals from China; imports (by weight) are way up even relative to the post Russian invasion period
Show more

A different way of looking at trade --
trade in kilos
Europe now imports (by weight) more machinery, electronics and cars from China than from the rest of the world combined
1/3
Show more

A different way of looking at trade --
trade in kilos
Europe now imports (by weight) more machinery, electronics and cars from China than from the rest of the world combined
1/3
Show more
The acceleration in China's auto exports this year, off an already high base, has been stunning -- and it is a big reason why the EU felt compelled to change its trade paradigm. Like nothing the world has seen in the past ...
Show more

a) It is true that the CNY has never been so strong that Chinese exports systematically under-perform global trade
b) that doesn't mean that the CNY doesn't have an impact on trade flows/ net exports -- China's surplus tends to expand when exports outperform global trade, while being more or less constant when exports growth with global trade
all ears if someone has a credible aggregate overcapacity variable and wants to throw that into a standard trade regression ...
but the easy way to think of it is that Chinese overcapacity stays at home when the CNY is strong and flows to the world when the CNY is weak
this chart, incidentally, fully supports the IMF's work showing a 10 pp move in the RER changes net exports by about 1.5 pp v baseline
Show more

There is a clear asymmetry at play. The long term correlation is very low. What do I mean? Look at right side of the graph: the currency declined and exports grew above trend. That makes sense and it's observable.
Now look at the left side: the currency grew significantly more expensive but exports kept growing on trend.
This tells is two key things. First, there is a clear asymmetry in how Chinese trade responds to changes in the value of the RMB. Just because exports increase when the currency declined, do not expect exports to decline (or though not pictured here imports to increase).
Second, there are clearly missing variables that would help explain why we are seeing the results we are seeing. As a simple example, the mass of Chinese over capacity is playing a significant role in boosting exports. This concept would be especially true considering imports. In short, do not expect a symmetric bounce in imports
Show more

Sefcovic briefed EU ambassadors today on his talks in China.
Per diplomatic sources, EU imports of Chinese hybrid cars will be capped at 350,000 per year from December 1, via the use of a safeguard measure.
This is what Commission proposed, still needs approved by capitals
Show more
But as policy advice and an honest assessment of the China challenge I found it a bit thin -- suck it up and move into higher value added niches doesn't cut it when China wants all those niches too, and has been quite successful in capturing many of them
/end
Show more
I am sure this reads well and appeals to many "ango-saxon" readers (and certain circles on the continent) who are apostles of creative destruction and the migration of Western economies out of high end manufactures to services ...
Show more

And part of the answer is that aggregates can mislead.
The US flow data is derived from the custodial data, and China's shift out of US custodians registers as a "fake news" net sales of bonds of US bonds
(depressing the total for Asia, as the shift registers as higher european purchases)
3/
Show more
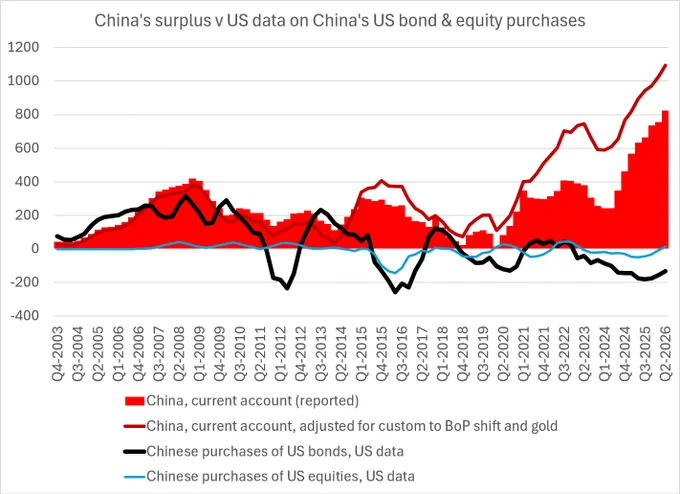
Part of the answer is that Asian investors (Singapore really matters here, as of course does Korea) are joining the party and buying US equities ... the US data shows ~ $250b in equity inflows from the big East Asian economies
2/
Show more

The missing flow problem
East Asia now runs a massive surplus ...
But almost none of it appears to flow into the US bond market
And the US needs an inflow to fund its deficit
1/
Show more

Have long enjoyed my dialogue with Kunal Shah, but disagree with him here -- the available data for q3 (July trade numbers, plus August import numbers) suggests a gigantic rewidening of the deficit in q3 and likely h2 ...
Show more


Worth noting the Trump admin has succeeded in reducing the trade deficit vs GDP - US trade deficit for 2026 is tracking at 2.5% the lowest it’s been for a while-
Huge success to be able to reduce this to 2% by the end of the presidency?
Exports / particularly AI led will increase materially
Show more


bills roll frequently; think the change in net duration in the market is a better measure that gross issuance (counts s-term bills multiple times)

Is this a joke?
The RMB is super undervalued, a major cause of China's excessive exports. The PBOC has only allowed slow RMB appreciation. It should rise far more quickly.
Putting brakes on RMB appreciation is a wrong step that should be met with international criticism.
Show more
This Fed note makes a compelling case that China's new balance of payments methodology actually reduced the quality (and certainly the consistency) of China's data (especially the headline current account). The IMF stats department should take note
Show more


Big news and a big story which is worth watching

EU floats customs union with U.K. to address “made in Europe” and tariff tensions with @pmdfoster

Highly recommend this piece by Toby Nangle (on duration supply from the hyper scalers)

Why the gold adjustment to China's current account is essential -- imports are set to go from 0.5 to 1.5 pp of GDP, with a considerable impact on the reported current account (and possibly the net export contribution)
Show more

1 trillion in net bills is 3% of GDP -- not a small share of the overall US fiscal deficit

🛑 T-bills total $8tn or 24.3% of marketable debt, above the Treasury Borrowing Advisory Committee’s ~20% suggested long-run share.
Nicely explained by Mr. Pettis
China's imports of gold also soared this year (they will add about a pp of GDP to China's import bill) and thus gold alone has had a significant impact on the overall 26 trade numbers
Show more

For those wondering why Setser strips gold imports out of China’s trade data, the reason is that gold can be purchased for two very different purposes. You can buy it for jewelry or manufacturing, or you can buy it as a store of value, much like buying a gold ETF, government bonds or property. The former is clearly a current-account transaction; the latter, when the asset is foreign, is a financial-account transaction.
The official balance-of-payments rules, however, do not make this distinction for physical gold. Nonmonetary gold is recorded as a good whether it is used for jewelry or held as a store of value. A foreign gold ETF is unambiguously an acquisition of a foreign financial asset, but an imported gold bar can be an almost perfect economic substitute and is nonetheless recorded as an import of goods.
This matters for China, especially in recent years. Chinese jewelry demand has collapsed relative to investment demand: in the first half of 2026, bar-and-coin demand reached a record 314 tons, more than twice the 136 tons of jewelry demand.
So Setser is making an analytical adjustment. Much of the recent surge in Chinese gold imports appears to reflect a shift in household and investor portfolios toward gold rather than a comparable increase in demand for goods and services. That is why stripping gold out of the trade balance can give us a better picture of the underlying goods imbalance.
Show more
China's trade surplus over the last 12ms looks flat.
But take out the surge in gold imports, and it is clearly still rising. It is now about a trillion dollars bigger than it was pre-pandemic
1/many
Show more











