
Joseph Wang
@josephwang
The Second Edition of Central Banking 101 is available now!
YouTube:
616 Following 212.3K Followers
Waller went from pleading "give disinflation a chance" just a few weeks ago to telegraphing "additional hikes" on account of higher energy prices, bigger AI buildout, and more tariffs.
Show more

Great analysis by a high IQ person in the industry.

AI Boom or Bust? – Manifold #122#
Are we in an AI bubble?
Analysis of AI CapEx, revenues, OAI+ANT burn rates.
AI revenue has to reach $ TRILLIONS per annum within the next few years (an increase of > 10x; compare total global software revenue of $1.5T today), or else the current CapEx spend will turn out to be a huge misallocation.
Separately, even if total AI revenue reaches these levels, OAI and ANT could still be overvalued due to revenue/margin compression from competition with other US or Chinese labs.
Chapters:
(00:00) - Conference Takeaways
(03:21) - AI Capability Leap
(07:36) - Both Things True
(08:46) - CapEx Debt Risks
(10:31) - Trillion Revenue Hurdle
(18:32) - Spend Plateau Signals
(31:45) - IPO and Bubble Fallout
Show more


US Equity Supply Is Back: Net Issuance Turns Positive After 20 Years
The 20-year shrinkage of US public equity supply is over. Net issuance: +$45bn in Q1, +$152bn in Q2, the largest quarter ever. Anthropic ($100bn), SB Energy ($50bn) and Inspire Brands ($20bn) are still to come. Supply will be a headwind for the S&P 500, or at the very least a tap on the brakes.
Show more

Deep dive into how Scott Bessent runs Treasury. In January, he confronted the agency’s undersecretary for terrorism and financial intelligence, yelling at him in front of aides and unleashing profanities. Bessent shouted so loudly that staff working nearby could hear him, according to people with direct knowledge of the matter, @schwartzbWSJ @jdawsey1 @PhilipWegmann @GZuckerman report.
People who have worked with Bessent said he often appears calm but can excoriate staff when he is frustrated. Some aides said they ask colleagues about the secretary’s mood before coming into contact with him, and trade advice on how to avoid him when he is angry. Several officials described feeling relieved when Bessent was away from the office.
But Trump has only pulled Bessent closer, empowering him to solve stubborn problems in the economy. Bessent’s defenders argue his intense approach to the job is an asset.
Show more


You’re Secretary of the… Treasury
… right?


PSA
We are now entering spot-up, vol-up territory
strong form
30 year TIPS at 3.4% is an amazing way to preserve wealth IMO.

Markets Weekly October 3, 2026
Bonds behave badly
Le spread
Anthropic IPO
Oil prices continue to drive rates, where the 10 year yield rises as headlines drive oil prices higher.

France 10 year swap spread show yuge stress👀


They’re blackmailing the EU to dump reserves ahead of the midterms. This week is pretty wild. All hands on deck, for sure. 🌶️🥵
Yields are rising in Europe as well because of higher energy prices. Global energy prices need to come down for global yields to come down.

A huge chunk of the AI spending just flows abroad, so you get Taiwan's GDP growing at 11% while U.S. growth has hovered around 2% the first two quarters.

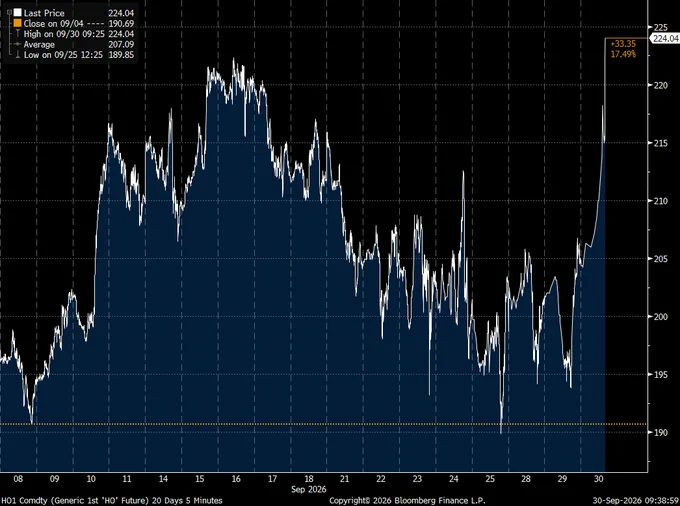
This didn't take long—US diesel prices now at a fresh all-time high above $224/bbl!
acute squeeze into today's contract expiry

This was fun to write! Gold is leaving Comex for the new interbank OTC market in Hong Kong. Inventories and price discovery are moving closer to the Asian gold markets.


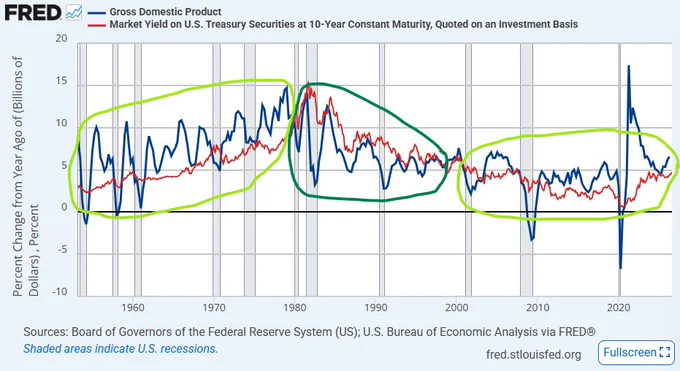
The thumbrule that says that the 10-year treasury yield should be roughly equal to nGDP growth is based on a cherry-picked historical anomaly. It only held true during a period in the mid-to-late 1990s, in the aftermath of the Volcker monetary tightness (when the 10-yr rate was actually higher than nGDP growth). During the expansions of the 1950s, 1960s, 1970s, 2000s, and 2010s, the 10-year was typically 2%-3% points below nGDP growth. Today, that would suggest a 4%-5% yield.
The claim that rates should be 6%-7% today b/c that's where nGDP growth is are even more dubious when considering current wage growth. For most of post-war history, 10-yr rates were 2%-3% below aggregate wage (COE) growth. That includes the boom of the late 1990s, which saw very strong growth. The numbers on that front may improve from here, but so far, they've been quite weak, which would suggest a 10-yr yield well below current levels.
Show more


Oil and rates continue to rise together ... see the chart of 10yr yields vs 12m oil contract price. The front-end of the oil curve might be more noise than signal still.


But if you really do want to go back to the GFC, this is what that looks like.

Market's now pricing a hiking cycle that takes us to around 5% September 2027. Seems ridiculous to me.











