

rf.extended
@rf_extended
Founder @extendedapp, formerly @revolut
Views my own. Info only. No advice, offer or solicitation. Not for persons in restricted jurisdictions.
885 Following 5.3K Followers
Extended is now Arc native. Excited for the next chapter, and looking forward to working with @jerallaire and the @circle team on a wide range of opportunities.
Why Extended is pursuing a regulated path in Europe
TLDR: European retail already trades inside licensed apps, and regulated platforms typically need regulated venues they can integrate. Extended is building one. Builder codes let partners plug Extended into their own product: through the existing venue for self-custody users where available, and through the regulated venue for regulated clients once live.
Europe has close to 10,000 fintech companies, and hundreds of licensed investment firms and credit institutions. Most are exploring new ways to engage their retail user base, and perps are consistently near the top of the list. All of them are potential clients for a regulated exchange.
That market opportunity drove our decision to build a regulated venue in Europe:
1. Retail is the user base we are building the regulated offering for. We have said before that sustainable growth is built on product quality, distribution and community rather than financial incentives. For a trading product, the largest pool of users is retail, and reaching it is a distribution problem.
2. Perp DEXs processed roughly $600 billion in volume over the past 30 days. CFD brokers alone show the size of the addressable market: around $30 trillion a month, with a large share of it in Europe. The largest platforms already earn most of their volume outside FX, in equities, indices, commodities and crypto. On-chain perps is a market we know well and intend to keep serving, but the larger opportunity sits next to it: tens of millions of retail traders already active on regulated platforms, many of whom have no access to perps today.
3. There are three retail markets at the scale that matters: the US, Europe and Asia. The US is the most contested, with many major exchanges and brokers competing for the same users and a long licensing path. Asia has high perps penetration but regulatory approaches vary by jurisdiction. Europe is where we are starting, and we will look at other regulated markets as and when it makes sense.
4. Regulated crypto derivatives in Europe have only recently expanded. Kraken, Coinbase and Bitstamp (owned by Robinhood) launched futures for EU clients over the past 18 months, each using regulatory infrastructure obtained through an acquisition of a licensed investment firm or exchange. That route is open to a handful of firms with the balance sheet for it, but for the far larger group of fintechs and brokers with users and no perps infrastructure, it is not. Our model is to offer builder codes on both venues: a way for partners to plug perps into their own apps, route users’ orders to the venue and earn a share of the fees. Self-custody wallets can integrate with the existing venue where available. Regulated brokers and fintechs will be able to use the regulated venue once it is live.
5. A regulated perps setup takes significant time and resources to build from scratch, and many fintechs lack the product and market expertise to run it well, starting with established market-maker relationships. For smaller players the economics may not work. For larger ones, regulated builder codes cut time to market, especially inside slow-moving large organisations, and deliver a quality product from day one.
6. The demand is clear. We are already in conversations with wallets, CFD brokers and fintechs across Europe, and we repeatedly hear the same request: a regulated venue with a broad range of crypto and RWA markets they can integrate.
Importantly, this does not change our DeFi offering or our commitment to the early community. The existing venue stays for crypto-native users where it is available. The regulated venue adds a new distribution channel and a new user base.
Europe is the first step. Over time, we expect to replicate the same model in other markets, including the US. Our plan is subject to the relevant regulatory authorisations, and we will share specifics as they are confirmed. At a high level, we have an initial route to market, followed by a transition to our own licences.
Disclaimer: This post is for informational purposes only and is not an offer, solicitation or recommendation. It contains forward-looking statements that are subject to change and to regulatory approval. Perpetual derivative contracts do not provide ownership of, or shareholder or other rights in, the underlying assets or companies. Trading involves leverage and significant risk, including possible total loss. Availability is subject to eligibility and jurisdictional restrictions.
Show more

A very productive week. Thank you to everyone who attended the Arc x Extended executive dinner, including the teams from @circle, @eToro, @bitpanda, and @Bitvavocom.
Europe is an important market for Extended, and conversations like these make the next steps considerably clearer.
Show more


What do we have here?👀
@extendedapp has the highest execution quality score of any exchange on DeFiLlama's REAL Ranking, including CEXs.
Compared to other DEXs, Extended also offers the lowest slippage on $10K orders.
Expect more.
Show more

RT @extendedapp: RFQ improvements
Following the feedback we received from the community, we've updated how orders are executed on RFQ mark…

Great to see perps making their way into everyday financial apps. Excited to see @PulsarMoneyApp pushing this forward.

We're partnering with @extendedapp to bring perpetual futures to Pulsar app.
Markets arrive in the money app. Accounts, card and balance stay exactly as they are.

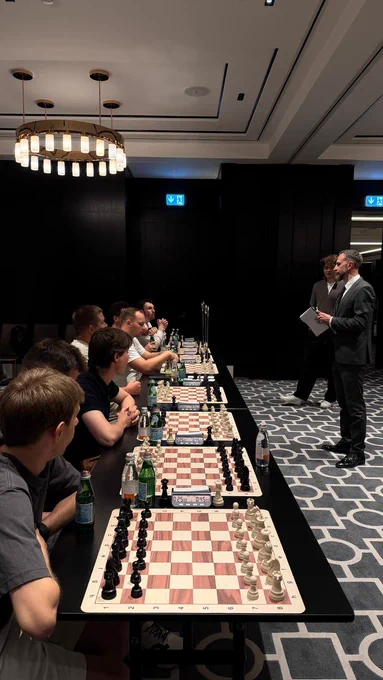
.Thanks everyone for joining us at the @extendedapp event. Many great conversations, ideas and chess games.


Over the past six months, we have spent significant time strengthening the protocol’s security architecture as Extended continues to scale. Throughout that work, we were guided by a fundamental reality of DeFi: defenders must protect against every possible code vulnerability and economic attack vector, while an attacker only needs to find a single successful path.
That does not make DeFi inherently unsafe. It means protocols should be designed not only to prevent incidents, but also to assume that failures are possible and limit their impact when they occur.
At Extended, this philosophy is reflected in several layers of protection:
- User funds are held in a dedicated Treasury contract that is intentionally kept separate from the trading application, making it significantly easier to audit and reason about.
- The trading engine, risk engine and other complex application logic operate through separate contracts and do not custody user funds.
- The Treasury contract incorporates circuit breakers that automatically pause withdrawals if abnormal withdrawal activity is detected.
- Where a circuit breaker is triggered, further withdrawals may require review and approval through the applicable security-review and multisig process.
- Cooldown periods and timelocks apply to certain sensitive Treasury upgrades and administrative actions, reducing the risk of immediate changes to critical controls.
Similar principles apply beyond smart contracts. Recent events reinforced the importance of strong access controls and limiting the impact of any single compromised account. We have since tightened permissions and strengthened controls around official communication channels and privileged access.
None of these mechanisms eliminates the possibility of exploits.
The objective is different. Rather than assuming perfect security, we make it significantly less likely that a single failure could compromise the entirety of user funds. Whether an issue originates from application logic, infrastructure, bridges, oracle providers, compromised accounts, operational mistakes or economic attack vectors, the goal is to contain its impact and minimise the amount of capital that can be affected.
These controls are designed to reduce the impact of potential failure scenarios, but they should not be interpreted as guaranteeing a maximum loss under every scenario.
Show more
Extended aimed to complete all key milestones by the end of H1. Since then, besides expanding the product, we've made significant progress on strategic partnerships and fundraising, both of which took longer than expected given their complexity.
As a result, one key milestone was pushed back: progressing the decentralisation roadmap. Yesterday, we announced that Extended is now working to decentralize the sequencing layer, laying the groundwork for its future tokenomics. We'll share more updates as the rollout continues.
While the timeline has shifted, our commitment to the early community hasn't. Specifically:
1. The current plan remains for 30% to be allocated to the early community (points holders).
2. The final number of points after slashing will not exceed the originally budgeted 70 million points. Slashing will take place in the coming weeks. Extended may make further adjustments before TGE if additional issues affecting programme integrity are identified.
3. Until the end of the program, we'll be distributing up to 600,000 points weekly.
Please note that eligibility for any airdrop will be subject to separate terms and conditions. Having no points slashed does not guarantee eligibility for an airdrop, any particular allocation, conversion rate or value.
We appreciate everyone's continued support. Our priority remains unchanged: building the right product, infrastructure, and distribution to create a sustainable protocol.
Show more

How Extended is building differently
When Extended launched, the aim was to make the product trust-minimised, seamless, high-performance, and broad enough to support perpetuals, spot, yield products and portfolio margin.
That foundation is now in place. The protocol combines a high-performance trading experience with on-chain settlement and verification. User funds are held in smart contracts, while the trading logic and risk engine are implemented on-chain. Every transaction is verified and settled directly on @Starknet - transparent, verifiable, and open source.
One part of that foundation has remained more centralised than the target architecture: the sequencer.
Extended is now working to decentralise the sequencing layer, separating transaction sequencing from settlement. The settlement chain will continue to handle custody, with final verification and settlement performed on the underlying public blockchain, while sequencing will be performed by Extended's native network.
On-chain order books exist today, but most high-performance trading systems still require trade-offs between performance, decentralisation, and custody. Extended changes that. This work is already underway, and we'll be sharing more details as the rollout progresses.
Show more
Glad to discuss the latest product and strategic milestones for Extended with @andyyy and @robbieklages.
More updates and more work ahead.

Perps is the centerpiece of this cycle and @extendedapp just spent six months building for it.
@rf_extended delivers a progress report on what the team has built:
"Tokenized vault, multi-asset collateral, spot markets. All shipped. Fundraise closed: eToro, Jump Crypto, Alber Blanc."
"Partnership with eToro. Perps: centerpiece of this cycle. Intense work, all for good. More announcements coming in weeks."
Show more

Having @eToro, @jump_ and Alber Blanc join @extendedapp as investors and partners marks an important milestone for the Extended.
We look forward to working together and will share more about what this means for Extended in due course.
Show more

It’s starting to become an extended DeFi family!
Following our acquisition of @ZenGo, proud to lead @extendedapp’s new funding round.
Another step forward in our strategy to bring seamless DeFi access to retail investors worldwide!
Show more

Besides allowing users to trade with ETH, wBTC and USDT as margin, multi-asset collateral on @extendedapp also unlocks simple cash-and-carry strategies: long spot, short perp and gain exposure to funding payments. As always, returns depend on funding rates, which are variable and change over time.
Show more

6 months of building. what's next?
TLDR: We focused on putting in place the product, partnership and governance foundations for the next phase of Extended. TradFi partnership, hundreds of new crypto and RWA markets, spot trading and further decentralisation are coming. Our approach to growth remains unchanged: no KOL round, no paid promotions, no paid PR, no podcast sponsorships and no paid market-making arrangements.
Over the past 6 months, the team at @extendedapp has been focused on a fairly simple objective: building the product, infrastructure and partnerships required to support the next stage of growth.
A lot of the work happened behind the scenes but we are now getting to the point where the pieces are starting to come together.
Product
Some of the key items are already live:
- Multi-asset collateral, allowing users to post wBTC, ETH and USDT alongside USDC. Besides expanding the collateral universe, it also unlocks simple cash-and-carry strategies directly on the platform.
- Full email onboarding, including gasless deposits and withdrawals. While not particularly exciting on its own, it unlocks fiat on/off-ramp integrations that are required to onboard non-native users.
- Significant improvements to UI stability, responsiveness and overall user experience, driven largely by user feedback collected over the past months.
Several important pieces are coming next:
- Spot trading, which we view as a table-stakes component of a complete exchange experience and an important UX improvement to multi-asset collateral.
- Opening up our lending infrastructure beyond the exchange itself, allowing users to deposit wBTC, ETH and USDT, borrow USDC and deploy capital elsewhere.
- New trading infrastructure that will unlock hundreds of additional crypto and RWA markets. Internally, this is the product initiative we are most excited about.
Growth
Over the same period, we have spent a lot of time thinking about how Extended should grow.
One principle remains unchanged: we do not pay for KOL promotions, PR, podcast sponsorships or market-making arrangements. This applies equally to cash, tokens and points.
Its a slower path and not the easiest one but over time we have become increasingly convinced that sustainable growth is built on product quality, distribution and community rather than financial incentives.
We have also completed a number of less visible but equally important initiatives:
- Finalised the legal and commercial framework for our first tradfi partnership, which unlocks some of the product initiatives mentioned above and establishes a foundation for future institutional integrations.
- Secured the majority of the long-term partners who will help operate, secure and govern Extended. We are proud of the quality of the organisations that chose to support the vision and will be sharing more details separately.
- Spent considerable time with our largest users and major ecosystem participants to gather feedback and ensure alignment around the long-term direction of the protocol.
- Remained committed to our original targets for early community rewards, despite certain things taking longer than anticipated.
This month is an important one for Extended. It will conclude the team's efforts over the past 6 months and mark the beginning of the next phase: further decentralisation, ecosystem expansion and the transition to a community-owned protocol.
Show more

during yesterday's HYPE rally, @extendedapp was the best dex to trade it in terms of liquidity, while offering up to 50x leverage


Extended surpassed $25M in Total Cumulative Revenue

What multi-asset collateral unlocks for @extendedapp's roadmap:
- Alongside multi-asset collateral, we have built spot trading infrastructure (all non-USDC liquidations already route through the native spot market), leveraged spot and a lending protocol.
- As the next step, we will open spot trading to users and expand lending beyond the Extended ecosystem to support broader DeFi use cases.
- Reasonably soon, we will multiply the number of crypto and TradFi markets available on Extended, while keeping liquidity and execution quality as top priorities and upgrading spot trading to support leverage.
While multi-asset collateral is only one part of the broader vision, it is foundational to Extended’s goal of building one margin account across all markets: hundreds of crypto and TradFi perpetual markets, leveraged spot, an open lending protocol, yield products (XVS), and other trading products.
Show more
What's unique about Extended’s native money market.
With multi-asset collateral now live, @extendedapp users can deposit ETH and wBTC (with USDT and EURC coming shortly) and use them as margin to trade perpetuals. When a user's USDC balance goes negative, borrowing is triggered automatically with the Extended Vault serving as the primary lender.
The key difference is how borrowing rates work.
Traditional crypto money markets typically operate through isolated lending pools, where interest rates depend only on utilisation of a specific pool. Collateral risk is managed separately through haircuts and borrowing limits.
Extended's setup is fundamentally different.
The Vault lends against multiple collateral assets simultaneously, while borrowing demand emerges dynamically from unrealised PnL. In this environment static global borrowing caps are not practical.
As a result borrowing rates depend on two dimensions:
- overall vault utilisation
- utilisation against a specific collateral asset.
This means borrowing USDC against ETH can be cheaper than borrowing against BTC if system-wide exposure to ETH is lower.
The second layer is how borrowing is allocated.
When a user has multiple collateral assets, the system automatically routes borrowing through the lowest-rate collateral first, minimising the effective cost of capital.
Example: if a user has a negative USDC balance backed by both ETH and wBTC collateral, and ETH borrow rates are lower than BTC, the system will allocate borrowing against ETH first before routing the remainder against BTC, continuously reducing the effective cost of capital.
The result is a system where:
- users automatically receive the cheapest borrowing allocation across their collateral portfolio
- Extended maintains granular risk control over exposure to different collateral assets backing borrowed USDC
- vault depositors earn additional yield directly from trading activity.
Show more

From our conversations with TradFi brokers, it’s clear that moving to 24/7 is quickly becoming table stakes.
To get there, most are looking at two routes: launching perps (either in-house or via partners) or extending CFDs to 24/7 and hedging the exposure externally.
When discussing the second approach, hedging CFD exposure with perps (instead of futures, leveraged spot, etc.), two structural differences stand out:
1. Deterministic liquidation vs operational margining. In TradFi, margining is rule-based but involves operational processes and potential grace periods, while in perps liquidation is fully deterministic and continuous, ensuring individual account and system-wide solvency without credit assumptions.
2. Managing funding vs rollover / borrow costs. Perp funding is realized more frequently (hourly / 8-hour), and can be significantly more volatile as it reacts in real time to positioning imbalances, compared to the smoother, benchmark-driven cost of carry in futures and financing markets.
None of those are blockers to a wider institutional adoption of perps, but rather observations on how traditional players are already adapting their ways of working to benefit from perps and DeFi.
Show more

State of liquidity and execution on @extendedapp v5 - TradFi Edition
By popular demand, we're taking our liquidity analysis beyond crypto for the first time, this time covering TradFi markets: US equities (NVDA, MSTR, INTC, CRCL), precious metals (XAU, XAG), and the Nasdaq Index (NDX), across @extendedapp, @HyperliquidX (via @tradexyz), and @Lighter_xyz.
Methodology
1. We measured slippage (buy/sell) on the above assets for $10k and $100k market orders across the three exchanges every 30 seconds from Mar 24, 07:11 UTC to Mar 31, 11:44 UTC (20,657 snapshots)
2. We ranked each exchange by market and clip size for both slippage and total cost of execution (slippage + exchange fee), where 1 = best and 3 = worst
3. Fees applied: Extended 2.5 bps, Hyperliquid base rate 4.5 bps, Lighter 0 bps
4. The dataset also includes charts showing how slippage evolved over the tracked period
5. NDX is listed as XYZ100 on Hyperliquid and QQQ on Lighter
Results:
Slippage
- On equities and metals, Extended leads at $10k clip sizes, while Hyperliquid is better at $100k
- On indices (NDX), Hyperliquid leads at both clip sizes
Total cost of execution - where it gets interesting
- Equities at $10k: Extended is the cheapest across all 4
- Equities at $100k: Hyperliquid leads across all 4
- Metals: Lighter's zero-fee model gives it the edge on both XAU and XAG at $10k, and on XAU at $100k
- Indices (NDX): Hyperliquid leads at both clip sizes
What this means
1. For equity trading at smaller sizes, Extended liquidity and fee structure make it the most efficient option overall
2. For larger orders, Hyperliquid has deeper liquidity and wins on total cost
3. Lighter's zero-fee model gives it a real edge in metals, though less so in equities
It’s still early days for on-chain TradFi liquidity. There’s room for all exchanges to improve, and we'll keep tracking it.
Full dataset:
Show more

In light of recent security incidents in the space, we follow a strict set of principles in our approach to contract security:
1. No deployments without audits conducted by at least two independent external firms
2. Critical controls are governed by a multisig, with signers distributed across geographies
3. Circuit breakers are in place for certain operations to pause the contract
For security reasons, we do not disclose implementation details of these mechanisms but safety of the user funds is the top priority for the team.
Show more










