

Jason's Chips
@jasonschips
AI/semis buyside investor | All views my own, not financial advice
73 Following 10.1K Followers
🔔 The Daily Semi-Cap — 2026-10-08
📊 SMH: $607.27 (-2.84% vs prior trading close)
• OpenAI told investors its end-September annualized revenue was approaching $50B, rather than the roughly $70B figure inferred in earlier investor comparisons. The difference largely reflects whether sales through cloud partners are counted. AI-linked stocks sold off as investors revisited the gap between massive infrastructure commitments and the revenue directly captured by model developers.
• Samsung Electronics' preliminary Q3 guidance puts sales near KRW195T and operating profit near KRW107.4T, versus KRW86.06T and KRW12.17T a year earlier. That is an extraordinary memory-cycle acceleration, though these are company estimates, not final segment results. The scale raises the stakes for its forthcoming breakdown of HBM and conventional memory economics.
• GlobalFoundries signed a five-year, $2B manufacturing agreement to supply silicon interposers for TSMC's CoWoS advanced packaging from Malta, New York. The first U.S. source is expected to ramp volume production in the first half of 2028. Packaging capacity and supply-chain geography are becoming part of the AI accelerator bottleneck equation.
• TSMC's September sales disclosure put third-quarter revenue at roughly NT$1.49T, a record and above market expectations. The monthly print captures continued demand for leading-edge AI wafers, but it is not the full earnings report: margins, profit and the next capacity outlook still await the company's quarterly results. Foundry throughput remains the hard-demand counterpoint to softer AI monetization sentiment.
• INNIO extended its engine-supply partnership with Aggreko through 2031, including at least 450 MW of Jenbacher Type 4 capacity in 2027 and J620 engines starting in 2028. Its modular power systems serve data centers as well as other critical loads. This is a concrete capacity commitment for the behind-the-meter power market facing grid connection delays.
• ASML and optics partner Zeiss outlined a possible Hyper NA successor to today's High NA EUV systems in roughly a decade. Their paper describes features as small as 5 nanometers while reusing the current light source, but ASML has not committed to building the machine. The long runway underscores how much advanced-chip scaling still depends on lithography optics.
Show more
🔔 The Daily Semi-Cap — October 7, 2026
📊 SMH: $625.03 (-1.18% vs prior trading close)
• Broadcom is working to arrange more than $50B of financing for OpenAI custom AI chips, with Apollo and Blackstone among lenders in early discussions. Oracle and SpaceX are separately exploring enormous hardware financings. The new bottleneck may be balance-sheet capacity: chip demand is real, but procurement and cloud revenue arrive on different clocks.
• Blackstone-backed AirTrunk plans another $1B investment in its Inzai, Japan, data-center campus, including liquid-cooling infrastructure for AI workloads. The expansion pushes hyperscale spending beyond chips into powered real estate and thermal systems; securing both usable capacity and cooling is becoming central to where accelerator clusters actually land.
• Aehr received approximately $6M of follow-on Sonoma burn-in orders for a hyperscale customer's second AI processor. Systems, modules and sockets will go to a Taiwan packaging-and-test partner over the next six months, ahead of an expected 2027 production ramp. Multi-zone thermal control becomes more valuable as AI packages grow larger and hotter.
• Lattice and Arm unveiled a server-platform collaboration pairing Arm AGI CPUs with Lattice FPGAs and AMI firmware for secure management and connectivity. The design puts programmable control alongside the CPU and baseboard controller, including standardized OCP module links. It broadens Lattice's AI-server content opportunity, but is not a disclosed volume order.
• Intel CEO Lip-Bu Tan says the company remains involved in Musk's Terafab venture even as Musk says his companies will build and operate the chip complex, not TSMC. That preserves Intel's prospective role for now, but neither a final foundry structure nor a production commitment has been announced; partnership speculation is not wafer capacity.
• San Francisco and Oakland approved 45-day pauses on new data centers while they assess electricity, water and air-quality impacts. San Francisco's measure also blocks expansions, including a proposed increase at NOVVA's Bayview site from 9 MW to 36 MW. Local permitting is now a measurable constraint on AI infrastructure timelines, not merely a political talking point.
Show more
🔔 The Daily Semi-Cap — October 6, 2026
📊 SMH: $632.50 (-0.22%)
📈 Earnings:
• PENG — $566.7M Q4 FY26 sales (est. $519.9M), $1.00 adjusted EPS (est. $0.77). Adjusted GM 28.8%; sales +68% YoY. FY27 sales outlook raised to ~$2.43B, with $4.45 adjusted EPS at the midpoint. Integrated Memory sales hit $340.8M (+158% YoY); shares rose after hours.
🔥 Major Developments:
• Marvell raised its FY28 revenue outlook to ~$20B at Investor Day and set a FY31 target of $70B–$90B, framing AI connectivity and custom silicon as the growth engines. Its estimated addressable market reaches ~$400B by calendar 2030.
• Google and Constellation signed a 20-year deal to add 890 MW of nuclear capacity through upgrades at 11 existing units in PJM, backed by more than $4.3B of Constellation investment. A separate 15-year agreement covers 2,700 MW of existing supply.
• Applied Materials and Intel expanded their R&D partnership across next-generation transistors, interconnects and advanced packaging, linking Applied’s Silicon Valley EPIC Center with Intel’s Hillsboro campus to accelerate AI-chip manufacturing technology.
Show more
JPMorgan on CoreWeave ($CRWV), May 8: Record bookings, but a lumpy buildout
JPMorgan says CoreWeave’s Q1 validated demand and financing progress, yet the path from signed AI compute contracts to revenue remains uneven. These are May 2026 figures, not a current-quarter update.
Key proof points:
• Q1 revenue of $2.08B beat consensus by ~6%; FY26 revenue guidance held at $12B–$13B.
• More than $40B of new Q1 commitments lifted backlog to $99.4B, up $32.6B sequentially (+49%).
• The 2026 exit ARR floor rose by $1B to $18B–$19B, but Q2 revenue guidance of $2.525B at the midpoint was ~7% below consensus.
• Ten customers had committed $1B+ each. Jane Street added $6B in Q1; financial-services backlog approached $10B.
Why it matters:
The debate is less whether AI compute demand exists and more whether CoreWeave can turn a huge contracted backlog into deployed, profitable capacity without overburdening the balance sheet. Customer diversification helps, but execution and funding still set the pace.
Capital and margin angle:
FY26 CapEx guidance increased to $31B from $30B on higher component prices; JPMorgan expected those costs to pass through without materially changing margins on previously booked deals. An $8.5B investment-grade-rated HPC-backed financing facility priced at an implied cost below 6%, easing—but not eliminating—the funding overhang.
JPMorgan view:
Neutral; December 2026 price target raised to $105 from $90. Its target uses ~42x estimated 2027 pro forma EBIT of $2.5B versus ~27x for its peer group. Growth and differentiation support the premium, in JPMorgan’s view, while debt, heavy CapEx and execution risk argue against chasing a smooth-growth narrative.
Show more
🔔 The Daily Semi-Cap — October 5, 2026
📊 SMH: $633.90 (+0.52%)
📈 Earnings:
• No new AI-infrastructure earnings released today.
🔥 Major Developments:
• Schneider Electric agreed to acquire industrial software maker PTC for $205/share in cash, valuing its equity at $22.6B. The deal would combine product-design and lifecycle data with Schneider’s energy and industrial operations software; closing is expected by Q3 2027.
• The U.S. Energy Department offered Vistra a conditional loan commitment of up to $4.2B to modernize and uprate three existing nuclear plants in Pennsylvania and Ohio. The projects would preserve nearly 4 GW and add 433 MW of capacity in the PJM region; funding still depends on final conditions.
• FUJI demonstrated SMT placement of Broadcom’s roughly 1.3 kg Tomahawk 6–Davisson co-packaged-optics switch with its NXTR machine in a joint evaluation with Broadcom and Celestica. It is a manufacturing feasibility milestone for AI networking hardware, not a production shipment announcement.
Show more
🔔 The Daily Semi-Cap — October 4, 2026
📊 SMH (Friday, October 2 close): $630.60 (+2.07% vs. Thursday, October 1 close)
📈 Earnings:
• No new AI-infrastructure earnings released today.
🔥 Major Developments:
• No material new AI-infrastructure developments today.
Show more
This is a good bear case. It’s very similar to what I’d write myself. All bulls should read it.

🔔 The Daily Semi-Cap — October 2, 2026
📊 SMH: $630.60 (+2.07%)
📈 Earnings:
• No new semiconductor earnings released today.
🔥 Major Developments:
• Amazon is exploring an $8B sale-leaseback of Nvidia Grace Blackwell systems already installed across more than a dozen U.S. data centers, using an investor-funded vehicle to preserve AI buildout capacity while shifting hardware ownership off its balance sheet.
• Toshiba plans to invest roughly ¥60B to double hard-drive production capacity for AI data centers by fiscal 2027, its first major HDD expansion in about five years; Seagate and Western Digital each fell roughly 10% on the supply news.
• Palantir named Armada its inaugural Certified Modular Data Center Partner, pairing Palantir’s Sovereign AI Operating System with U.S.- and allied-made modular infrastructure that can run on-grid, off-grid, or fully air-gapped.
Show more
🔔 The Daily Semi-Cap — October 1, 2026
📊 SMH: $617.81 (+1.45%)
📈 Earnings:
• No new semiconductor earnings released today.
🔥 Major Developments:
• JERA, Dell, and RHAELM signed an MoU to build national-scale AI infrastructure in Japan, starting with a $15B+, 400 MW project at JERA’s Chiba power station targeted to begin operations around 2028.
• Infineon inaugurated a new automated backend manufacturing hub in Bangkok covering assembly, test, and wafer test; the site can expand to five modules and grow from roughly 350 to 1,000 employees.
• Virginia released its 2026 Energy Plan, calling for data centers to bear their incremental grid costs, use demand flexibility and on-site storage, and prioritize lower-emission bridge power over new behind-the-meter gas combustion.
• Site development for Samsung’s Yongin semiconductor mega-cluster is set to begin this month, with six fabs planned and the first fab site targeted for delivery by the end of 2027.
Show more
🔔 The Daily Semi-Cap — September 30, 2026
📊 SMH: $609.00 (+0.35%)
📈 Earnings:
• MU — $54.23B rev (est $51.07B), $33.42 adj. EPS (est $31.61). Adj. GM 87.0%, revenue +379% YoY. Guided Q1 to $61.5B rev and $38.15 EPS at the midpoints, both above consensus; shares were roughly flat after hours.
🔥 Major Developments:
• Synopsys and OpenAI signed a multi-year agreement to jointly develop GPT-Synopsys, with OpenAI licensing Synopsys EDA tools and the companies sharing revenue and taking the product to market together.
• AWS signed a multi-year Synopsys silicon-IP agreement worth more than $1B covering custom chips including Graviton, Trainium, and Nitro, with Amazon becoming the lead customer for Synopsys' application-optimized IP business.
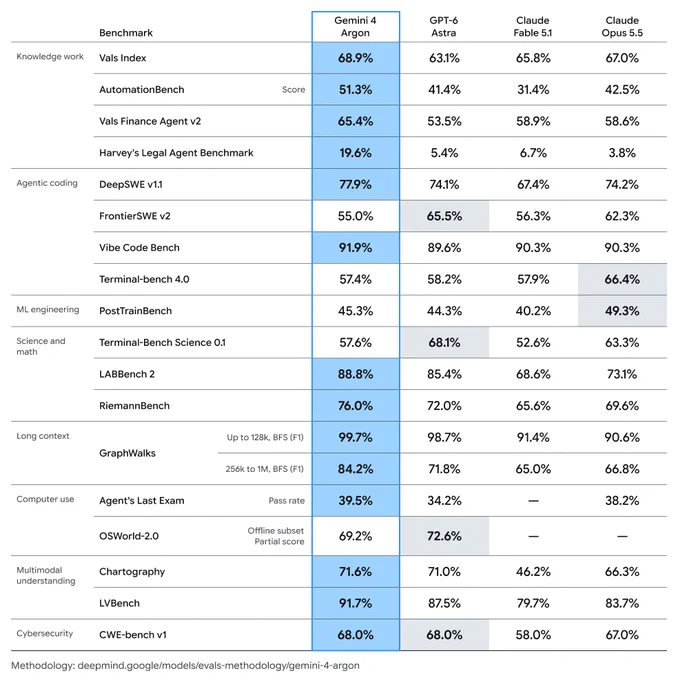
• Google unveiled Gemini 4 Argon for long-horizon coding, enterprise, and cybersecurity workflows, expanding maximum output to 1M tokens and initially rolling it out to trusted testers.
• Micron confirmed it is working with Nvidia on NVHBM, described as the industry's first custom HBM4E implementation, for next-generation GPUs and NVLink Fusion platforms.
Show more
Wow… it’s actually okay
Priced at $2/$10 which are Sonnet 5.5 levels. 1/2 price of opus/sol and 1/5 of fable/astra

Introducing Gemini 4 Argon – our new frontier model.
It’s built for complex workflows across coding, enterprise knowledge work, and cybersecurity defense – rolling out today to a set of trusted testers through our Fairwind Program.
Show more
🔔 The Daily Semi-Cap — September 29, 2026
📊 SMH: $606.90 (+1.15%)
📈 Earnings:
• No new semiconductor earnings released today.
🔥 Major Developments:
• OpenAI launched Dots, GPT-6.1 Sol at one-fifth of Astra's standard token pricing, and an Ultrafast tier offering up to 8x faster generation in Codex and 6x in the API.
• OpenAI's annualized revenue run rate is nearing $70B, up more than 70% since Q3 began, while the company seeks at least $30B at a $1.4T valuation.
• Anthropic has $252B of non-cancelable compute obligations across Microsoft, Google, and Amazon, plus $161.2B of largely non-cancelable Broadcom TPU lease obligations.
• TrendForce projects blended HBM ASPs to jump 121% YoY in 2027 while supply remains constrained; 8-Hi products are expected to command a 10–20% price premium per Gb over 12-Hi products.
Show more
🔔 The Daily Semi-Cap — September 28, 2026
📊 SMH: $600.01 (-1.08%)
📈 Earnings:
• No new semiconductor earnings released today.
🔥 Major Developments:
• Nvidia authorized an additional $150B of share repurchases, lifting its remaining buyback authorization to $235B through fiscal 2028. It also launched an open agent-safety stack pairing the OpenShell secure runtime with a BlueField-4 DPU-based Sentry watchdog.
• AMD agreed to acquire Fei-Fei Li’s World Labs for approximately $8.2B in stock, bringing spatial-intelligence and model research in-house to shape future AI hardware, software and systems. Li will join AMD as chief scientist.
• Meta launched Meta Enterprise Platform to bring Muse, Meta Business Agent, Muse API and Muse Code to businesses and developers. Former MongoDB CEO CJ Desai will lead the new unit and report directly to Mark Zuckerberg.
• Synopsys unveiled its Autopilot platform and AgentEngineer portfolio for autonomous silicon-to-systems workflows. More than 50 engagements are underway, with general availability planned by year-end.
Show more

Excellent work from Jason...and it's free to read 😍

Excellent Sunday reading!

Bloody hell what a report by Jason. Still going through it, highly recommended
Wow. $LITE is VCSEL pilled!

so this is what the singularity feels like

🔔 The Daily Semi-Cap — September 18, 2026
📊 SMH: $573.00 (+2.21%)
📈 Earnings:
• No new semiconductor earnings released today.
🔥 Major Developments:
• Nvidia-backed Nscale filed for a U.S. IPO under the ticker NSCL, disclosing $103.4B of active and contracted total contract value as of August 31.
• SK hynix subsidiary Solidigm is evaluating its first U.S. NAND fab, targeting an East Coast production base as AI-driven enterprise SSD demand tightens supply.
• CXMT is preparing a NAND R&D production line at its new Beijing fab, expanding beyond DRAM and discussing AI and supercomputing storage applications with prospective customers.
• SK hynix’s U.S. ADR will enter SMH at an approximately 5% weight effective September 21, replacing Skyworks and driving an estimated $3.4B of passive demand.
Show more
🔔 The Daily Semi-Cap — September 17, 2026
📊 SMH: $560.61 (+2.76%)
📈 Earnings:
• No new semiconductor earnings released today.
🔥 Major Developments:
• Generac signed a long-term agreement to supply backup generators for Amazon data centers, with about $2.4B of initial deliveries expected in 2027-2028 and potential payments reaching $8B.
• Crusoe raised $3.9B in a Series F to expand its AI factories, modular infrastructure, and cloud platform.
• CoreWeave launched a $3B convertible-note offering and an at-the-market program for up to 35M shares as it funds a contracted power footprint that has reached roughly 4.2 GW.
• Nebius will raise on-demand H100, H200, B200, and B300 GPU rental prices by about 20% on October 1, reinforcing tight AI-compute supply and cloud pricing power.
Show more











