Search results for 0418黄金裔紡がれた物語併せ
0418黄金裔紡がれた物語併せ community
One keyword maps to one global community path.
People
Not Found
Tweets including 0418黄金裔紡がれた物語併せ
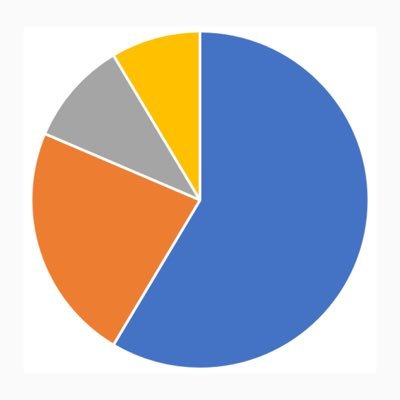
World Currencies vs. the U.S. Dollar
One-Year Change As of June 30, 2026:
🇨🇴 Colombian peso: +19.2%
🇮🇱 Israeli shekel: +13.2%
🇭🇺 Hungarian forint: +8.9%
🇿🇦 South African rand: +8.1%
🇲🇽 Mexican peso: +7.7%
🇨🇳 Chinese yuan: +5.6%
🇦🇺 Australian dollar: +5.2%
🇧🇷 Brazilian real: +5.2%
🇲🇾 Malaysian ringgit: +3.1%
🇳🇴 Norwegian krone: +1.8%
🇨🇱 Chilean peso: +1.0%
🇪🇬 Egyptian pound: +0.8%
🇭🇰 Hong Kong dollar: +0.1%
🇦🇪 UAE dirham: 0.0%
🇶🇦 Qatari riyal: 0.0%
🇸🇦 Saudi riyal: -0.2%
🇷🇺 Russian ruble: -0.4%
🇨🇿 Czech koruna: -1.1%
🇸🇬 Singapore dollar: -1.7%
🇨🇭 Swiss franc: -1.8%
🇹🇭 Thai baht: -2.3%
🇸🇪 Swedish krona: -2.4%
🇪🇺 Euro: -3.0%
🇩🇰 Danish krone: -3.1%
🇬🇧 Pound sterling: -3.4%
🇨🇦 Canadian dollar: -4.1%
🇵🇱 Polish złoty: -4.2%
🇳🇿 New Zealand dollar: -6.8%
🇹🇼 Taiwan dollar: -8.2%
🇵🇭 Philippine peso: -8.2%
🇮🇩 Indonesian rupiah: -9.3%
🇮🇳 Indian rupee: -9.4%
🇯🇵 Japanese yen: -11.3%
🇰🇷 South Korean won: -12.6%
🇹🇷 Turkish lira: -14.6%
🇦🇷 Argentine peso: -18.9%
Source: Deutsche Bank, Bloomberg Finance LP.
Show more

Tesla is still dominating. In the first half of 2026, they secured over 52% of the U.S. EV market.
1. Tesla: 52.3% — 242,100 units sold
2. Chevrolet: 6.1% — 28,267
3. Hyundai: 5.8% — 26,936
4. Cadillac: 4.7% — 21,855
5. Rivian : 4.7% — 21,770
6. Toyota: 4.7% — 21,767
7. Ford: 3.6% — 16,606
8. Kia: 2.7% — 12,627
9. BMW: 2.4% — 10,790
10. Subaru: 2.2% — 10,064
11. Honda: 1.8% — 8,407
12. Lexus: 1.7% — 7,814
13. GMC: 1.4% — 6,645
14. Lucid: 1.1% — 5,208
15. Volvo: 0.9% — 3,964
16. VW: 0.8% — 3,768
17. Mercedes: 0.6% — 3,010
18. Porsche: 0.6% — 2,967
19. Other Brands: 0.6% — 2,596
20. Nissan: 0.4% — 1,774
21. Audi: 0.4% — 1,697
22. Genesis: 0.1% — 560
23. Dodge: 0.1% — 534
24. Jeep: 0.1% — 418
25. Mini: 0.1% — 307
26. Acura: 0.0% — 108
(Data Via Cox Automotive Q2 2026 EV sales)
Show more


$PGR(Progressive)
5.8.1 快照与技术选股归属:现价222.88,市值129.58B,52周区间189.2到239.38,现金及等价物138.0M,短期投资10005.0M,流动性合计10143.0M,季度经营现金流3607.0M为正,跑道不适用(经营现金流为正,不依赖现金消耗),年度财报12/31/2025收入87671.0M,净利润11308.0M,研发无M,资本支出-348.0M,季度财报6/30/2026收入23609.0M,净利润3311.0M,流动比率nan%,毛利率17.18%,营业利润率16.54%(数据来源:个股基本面快照,2026-10-14);技术选股D组硬条件命中,分数58.55,获利盘93.15%,套牢盘6.85%,90%集中度6.92(数据来源:技术选股,2026-10-14)。
5.8.2 主营业务与产品技术亮点:Progressive是美国车险龙头,主营个人汽车保险、房屋保险与商业保险。核心技术亮点包括直接分销与代理人双渠道,基于驾驶行为的UBI定价技术,理赔数字化与快速结算能力。本条不写数字。
5.8.3 事件促发点:2026-10-14 Progressive发布财报,预期EPS为4.46,涉及季度业绩,量级判断重大,方向待定(数据来源:未来5日财报日历,2026-10-14)。暂无其他已公开促发点。
5.8.4 大行研报与消息汇总:目标价均值无,买入无,持有无,卖出无(数据来源:Nasdaq分析师库,2026-10-14)。Barclays目标价246上调至247,上调0.4%,头部国际大行,距现价16.4%(数据来源:MarketBeat 2026-10-07);HSBC目标价221下调至216,下调-2.3%,非头部,距现价1.79%(数据来源:MarketBeat 2026-10-07)。消息面:Zacks对PGR发出混合展望(Foreign Policy Journal 2026-10-13)。
5.8.5 关键价位、触发与失效:日线支撑筹码峰206.04距现价8.17%,日线压力20日高223.78距现价0.4%,周线支撑周线MA10为216.7距现价2.77%,周线压力52周高239.38距现价7.4%(数据来源:个股筹码四元组与关键价位,2026-10-14)。触发条件为放量突破20日高223.78,失效条件为跌破筹码峰206.04。资金共振同向项数2项(数据来源:3.1节,2026-10-14)。
5.8.6 情景:牛档239.38(周线压力52周高),基准档223.78(日线压力20日高),熊档206.04(日线支撑筹码峰)。从现价到周线压力空间7.4%。
5.8.7 结论:等触发,1到2周期望幅度至223.78约0.4%,赔率中性,建议观察,最大风险是财报不及预期。第一目标223.78,第二目标239.38。
5.9 $BIIB(Biogen)
5.9.1 快照与技术选股归属:现价228.9,市值33.82B,52周区间138.0到238.24,现金及等价物3008.5M,短期投资807.2M,流动性合计3815.7M,季度经营现金流448.9M为正,跑道不适用(经营现金流为正,不依赖现金消耗),年度财报12/31/2025收入9890.6M,净利润1292.9M,研发1778.6M,资本支出-153.8M,季度财报6/30/2026收入2736.0M,净利润97.5M,流动比率267.9%,毛利率75.69%,营业利润率18.83%(数据来源:个股基本面快照,2026-10-14);技术选股D组硬条件命中,分数38.68,获利盘97.73%,套牢盘2.27%,90%集中度11.81(数据来源:技术选股,2026-10-14)。
5.9.2 主营业务与产品技术亮点:Biogen是生物技术公司,主营多发性硬化、阿尔茨海默病与神经科学药物。核心技术亮点包括神经科学管线深度,阿尔茨海默病抗体药物,与Eisai等合作伙伴的全球商业化能力。本条不写数字。
5.9.3 事件促发点:2026-10-12 JPMorgan升级至Overweight,目标价210上调至300,涉及评级与目标价,量级判断重大,方向利多(数据来源:MarketBeat 2026-10-12)。暂无其他已公开促发点。
5.9.4 大行研报与消息汇总:目标价均值241.96,区间175.0到300.0,买入17家,持有6家,卖出1家,下期EPS预测12.41(Dec 2026),近4周EPS上修2家下修1家(数据来源:Nasdaq分析师库,2026-10-14)。JPMorgan升级至Overweight,目标价210上调至300,上调42.9%,头部五大,距现价32.91%(数据来源:MarketBeat 2026-10-12);UBS目标价240上调至270,上调12.5%,头部国际大行,距现价21.7%(数据来源:MarketBeat 2026-10-09);BMO目标价未披露至220,来源弱,非头部,距现价-5.12%(数据来源:MarketBeat 2026-10-12)。消息面:无。
5.9.5 关键价位、触发与失效:日线支撑筹码峰217.12距现价5.43%,日线压力20日高238.24距现价4.08%,周线支撑周线MA10为221.97距现价3.03%,周线压力52周高238.24距现价4.08%(数据来源:个股筹码四元组与关键价位,2026-10-14)。触发条件为放量突破20日高238.24,失效条件为跌破筹码峰217.12。资金共振同向项数3项(数据来源:3.1节,2026-10-14)。
5.9.6 情景:牛档238.24(周线压力52周高,与日线压力同位),基准档217.12(日线支撑筹码峰),熊档221.97(周线支撑周线MA10)。从现价到周线压力空间4.08%。
5.9.7 结论:可买,1到2周期望幅度至238.24约4.1%,赔率中性偏多,建议半仓,最大风险是神经科学药物竞争加剧。第一目标238.24,第二目标无更高参照,突破后重算。
Show more

JAPAN'S FINAL Q2 GDP ROSE AN ANNUALISED 1.4%, UP FROM THE PRELIMINARY 1.1% BUT BELOW THE 1.8% ESTIMATE, WITH QUARTERLY GDP UP 0.4% IN LINE WITH THE ESTIMATE AND THE DEFLATOR UP 2.6% YEAR-ON-YEAR.

CHOOSE YOUR FIGHTER
Warren Buffett vs Stanley Druckenmiller
Buffett stepped down as Charman of Berkshire Hathaway $BRK.B today. Druckenmiller has never had a losing year in more than 30 years.
Here are their full portfolios as of Q2 2026.
BERKSHIRE HATHAWAY
- Apple $AAPL: 22%
- American Express $AXP: 17%
- Google $GOOGL: about 12.6% across both share classes
- Coca-Cola $KO: 11%
- Bank of America $BAC: 9.2%
- Chevron $CVX: 4.7%
- Occidental $OXY: 4.3%
- Chubb $CB: 3.9%
- Moody's $MCO: 3.7%
- Kraft Heinz $KHC: 2.6%
- DaVita $DVA: 2.1%
- Delta $DAL: 1.8%
- SiriusXM $SIRI: 1.2%
- VeriSign $VRSN: 0.8%
- Kroger $KR: 0.7%
- Liberty Live $LLYVA: about 0.6% across both share classes
- Ally $ALLY: 0.4%
- Lennar $LEN: 0.4%
- New York Times $NYT: 0.4%
- Capital One $COF: 0.2%
- Louisiana-Pacific $LPX: 0.1%
- Nucor $NUE: 0.1%
- Macy's $M: 0.1%
- NVR $NVR
- Jefferies $JEF
- D.R. Horton $DHI
DUQUESNE FAMILY OFFICE
- Natera $NTRA: 17%
- Insmed $INSM: about 5.7% in shares and calls
- Taiwan Semi $TSM: 5.4%
- Brazil ETF $EWZ: about 5.1% in shares and calls
- Amazon $AMZN: about 4.6% in shares and calls
- STMicro $STM: 4.5%
- S&P 500 Equal Weight $RSP: about 3.7% in calls and shares
- Fox $FOXA: about 2.8% across both share classes
- YPF $REPYY: 2.7%
- CDW $CDW: about 2.7% in shares and calls
- BBB Foods $TBBB: 2.3%
- Google $GOOGL: 2.3%
- Seagate blockstack:native: 2.3%
- United Airlines $UAL: 2.1%
- Sea $SE: 2.0%
- NewAmsterdam Pharma $NAMS: 2.0%
- Russell 2000 ETF $IWM: 1.9% in calls
- Sandisk $SNDK: 1.5%
- Revolution Medicines $RVMD: 1.4%
- S&P 500 ETF: 1.3% in calls
- Bitdeer: 1.2%
- CRH: 1.1%
- Delta: 1.1%
- Tesla $TSLA: 1.0% in calls
- Fluor: 1.0%
- D.R. Horton: 0.9%
- Coupang: 0.9%
- AMD: 0.8%
- Palo Alto Networks: 0.8%
- Cleveland-Cliffs: 0.8%
- Hut 8: 0.7%
- Caris Life Sciences: 0.6%
- Argentina ETF: 0.6%
- Woodward: 0.5%
- Meta: 0.5% in calls
- Nuvation Bio: 0.5%
- Protagonist Therapeutics: 0.5%
- Roku: 0.5%
- Cavco: 0.5%
- ADMA Biologics: 0.4%
- Hyperliquid Strategies: 0.4%
- Rambus: 0.4%
- Rhythm Pharmaceuticals: 0.4%
- Champion Homes: 0.4%
- Daktronics: 0.4%
- PureCycle: 0.4%
- Southern Copper: 0.4%
- Linde: 0.4%
- Entegris: 0.4%
- Teva: 0.4%
- Unity: 0.4%
- Aeva: 0.4%
- Riot Platforms: 0.4%
- Qnity Electronics: 0.4%
- Equinix: 0.4%
- Lam Research: 0.4%
- Definium Therapeutics: 0.3%
- Belite Bio: 0.3%
- 10x Genomics: 0.3%
- Wabtec: 0.3%
- Eli Lilly: 0.3%
- Xenon Pharmaceuticals: 0.3%
- Olema Pharmaceuticals: 0.2%
- Repligen: 0.2%
- Rocket Companies: 0.2%
- Baidu: 0.2%
- Arm: 0.2%
- Carvana: 0.2%
- Reddit: 0.2%
- Alcoa: 0.2%
- Thermo Fisher: 0.2%
- Danaher: 0.2%
- F5: 0.2%
- Vista Energy: 0.2%
- Skeena Resources: 0.2%
- JBS: 0.1%
- Monte Rosa Therapeutics: 0.1%
- Relay Therapeutics: 0.1%
- DBV Technologies: 0.1%
- CCC Intelligent Solutions: 0.1%
- UWM Holdings: 0.1%
- Navitas Semiconductor: 0.1%
- Solstice Advanced Materials: 0.1%
- FTAI Aviation: 0.1%
- Beam Therapeutics: 0.1%
- Aurora Innovation: 0.1%
- IREN: 0.1%
- Grupo Financiero Galicia: 0.1%
- Wave Life Sciences: under 0.1%
Both own Google, Delta and D.R. Horton. Neither owns Nvidia $NVDA.
Show more


Last wk, S&P/Nas/Mag7 +0.4%/+0.1%/-0.8%. Cooler inflation (CPI, PPI) & economic data (consumer sentiment, retail sales) but +5% oil steepened the yield curve but lowered odds of a rate hike.
Looking forward, I continue to believe the impact of Agentic AI with the advent of OpenClaw on January 30th has at least a year to run:
1) Token production has gone up roughly ~7.5x from the end of January more than offsetting the nearly 50% token cost reduction seen since open-weight model usage started to take off in May.
2) Combined annualized run-rate revenues for OpenAI and Anthropic which ended last year at $29B seems to be around $100B currently with Anthropic getting profitable in Q2.
3) Capex from the Big6 hyperscalers accelerated from 84% y/y/ in CQ1 to 92% in CQ2 with forecasts for nearly 100% in Q3. But this is being supported by cloud revenue growth at the 3 Big Public cloud vendors of $AMZN $MSFT $GOOGL accelerating from 23% y/y in Q1:25 to 35% in Q1:26 to 43% in Q2:26. Arguable more important is public cloud operating margins expanded from 34% to 37% and 39% during those time periods.
4) The $500B financing deal backstopped by up to $125B from $NVDA adds even more lower cost money to fund AI capex spend for the non-hyperscaler players. Nvidia gained 0.5% last week.
5) The liquidation of Situational Awareness and retail accounts during July cleared out some of the frothiness in the AI related names
In terms of negatives:
1) The cost of money (yields on government bonds) remain near the highest levels for the 30 yr tenor at 5.3% since 2007.
2) Given large scale offensive US military actions are seemingly off the tablein favor of financial sanctions, probably driven by current election polls, I now believe Iran is likely to hold the Strait of Hormuz hostage until past the US mid-terms. This would be akin to them releasing the US hostages in 1981 (they were held for 444 days) just hours after President Reagan was sworn in replacing Carter. There were severe financial sanctions then also.
3) Since 1990, which happens to be the Gulf War, from the end of July through November 9th, which covers the reaction to all mid-term results, the performance is worse than non mid-term years. For mid-term years the median S&P500 gain from 7/31-11/9 is 0.9% with gains 56% of the time but the median peak loss from 7/31 is 6.2% (intra-period median peak loss of 9.9%.) For non mid-term years the median gain is 2.7% from 7/31-11/9 with gains 59% of the time and the median peak loss from 7/31 is 3.5% (intra-period median peak loss of 5.2%.) This year with the momentum seen by the Socialists which are not big business friendly, I see more risk than normal.
4) The easy money on the AI technical rebound from oversold levels on 7/29 due to the forced sale by Situation Awareness is probably over. There were negative stock reactions to headline beat and raise earnings on both revs & EPS for AI infrastructure winners $CSCO (-8% for the week but still up +45% YTD), $AMAT (-6%/+97%) and $COHR (-14%/+77%). While negatives can always be found, their biggest crime was arguably their recent bounce from 7/29-8/7 of 8%, 24% and 71% respectively and their market beating YTD gains.
In summary, I remain bullish. Even from the end of July through November 9th during mid-term years since 1990, the S&P has an additional median gain of 4.2% to its peak before giving some of that back closer to the election. Given some of the negatives, especially the reaction to solid earnings data, I would add some hedges back on further market gains and get more selective. Consumer discretionary hedges should also make sense if oil is higher for longer.
I believe value should continue to accrue to the infrastructure layer which includes 1) the public cloud vendors such as Amazon, Microsoft, Google and 2) the semiconductor companies. $INTC, my favorite semi company, still gained 0.8% last week despite: 1) a $20B equity offering which causes ~5% dilution and 2) being up 178% YTD. This clears the funding overhang.
All the best in the week ahead.
Show more

Foreign born population of each country :
Jan 2001 Jan 2025
🇦🇹 8.7% 22.5%
🇧🇪 8.4% 20.2%
🇩🇰 4.8% 14.4%
🇫🇷 5.5% 14.0%
🇩🇪 8.9% 20.5%
🇬🇷 6.9% 11.0%
🇮🇸 3.1% 21.8%
🇮🇪 4.0% 23.3%
🇱🇺 37.5% 51.5%
🇳🇱 4.1% 16.8%
🇳🇴 4.1% 18.7%
🇸🇮 2.1% 15.5%
🇪🇸 3.4% 19.3%
🇸🇪 5.3% 20.8%
🇬🇧 4.3% 20.0%
Now add children born to foreign parents and the situation looks even worse.
We are living through the demographic annihilation of the people of Europe.
Show more

New: Inverse Cramer is crushing the Pelosi Tracker and the S&P 500 in 2026
Although many think Inverse Cramer is a fun 'meme portfolio', it's turned into a legit alpha strategy.
Since launch on 1/27/23, it's up 247%.
Here are its positions and how they're performing so far
1. BP p.l.c. $BP +19.7%
2. International Business Machines $IBM -17.3%
3. Progressive $PGR -7.2%
4. Adobe $ADBE +15.2%
5. Bank of America $BAC -1.1%
6. Stryker $SYK -12.8%
7. Intuitive Surgical $ISRG -1.4%
8. Boeing $BA -9.9%
9. JPMorgan Chase $JPM +3.8%
10. W.W. Grainger $GWW -5.1%
11. Johnson Controls $JCI +0.4%
12. Astera Labs $ALAB -21.1%
13. Coherent $COHR -17.8%
14. Nebius Group $NBIS -0.4%
15. KLA $KLAC -35.7%
For the $109,000,000 investing alongside on Autopilot
*For transparency, data as of 9/22/26 1:25 PM ET
Find link to full portfolio in the following tweet
Show more

During Tesla Cybercab launch week in Austin, I took a total of 12 paid Cybercab rides and kept every receipt.
TOTAL:
• 12 rides
• 29.7 miles traveled
• $108.34 total spent
• $3.65 average cost per mile
• 2 hours and 19 minutes riding around Austin in a Cybercab
• Compared to Uber and Waymo, every Cybercab ride was still ~30-50% cheaper
EACH OF MY CYBERCAB RIDES:
1/ Sept 3 — 7:23 PM
3.9 miles · 16 min · $8.70
≈ $2.23/mile
2/ Sept 3 — 7:53 PM
0.5 miles · 6 min · $4.65
≈ $9.30/mile
3/ Sept 4 — 6:52 AM
2.5 miles · 12 min · $6.99
≈ $2.80/mile
4/ Sept. 4 — 7:13 AM
2.4 miles · 11 min · $6.84
≈ $2.85/mile
5/ Sept. 4 — 7:39 AM
1.8 miles · 11 min · $6.16
≈ $3.42/mile
6/ Sept. 4 — 8:03 AM
1.4 miles · 8 min · $5.69
≈ $4.06/mile
7/ Sept. 4 — 8:20 AM
3.3 miles · 15 min · $7.90
≈ $2.39/mile
8/ Sept. 4 — 10:58 AM
4.0 miles · 19 min · $8.78
≈ $2.20/mile
9/ Sept. 4 — 11:58 AM
2.6 miles · 8 min · $7.08
≈ $2.72/mile
10/ Sept. 4 — 2:17 PM
2.8 miles · 11 min · $13.71
≈ $4.90/mile
11/ Sept. 5 — 12:57 PM
2.4 miles · 10 min · $16.18
≈ $6.74/mile
12/ Sept. 5 — 1:36 PM
2.1 miles · 12 min · $15.66
≈ $7.46/mile
One of the biggest things I learned from actually using Cybercab is that you cannot judge the economics from just one ride.
Pricing is dynamic.
Some of my longer rides came in cheaper around $2.20–$2.40 per mile.
Some of the shorter or higher-demand rides were much more expensive.
Sometimes, the Cybercab was even more expensive than the Model Y (Unsupervised) bc the demand was so high.
Some of the rides also became more expensive as Cybercabs became bookable on September 4 to the general public.
However, it’s hard for me to look at these receipts and not wonder how Uber and Lyft can compete if Tesla can scale Cybercab the way it wants to.
Uber and Lyft were built around connecting riders with human drivers.
That means every ride has to support a much bigger cost stack... like
1/ A human has to be paid.
2/ That person needs a car.
3/ That car has to be financed or purchased.
4/ It needs insurance.
5/ Maintenance.
6/ Fuel or charging.
7/ And then Uber or Lyft still needs its cut.
Cybercab attacks the biggest cost in that entire system which is the driver... there is no driver waiting to be paid at the end of the ride.
And Tesla is supplying the software.
Tesla can build the car.
Build the battery.
Build the autonomy system.
Operate the network.
Control the app.
Control the charging.
And the team designed the Cybercab from Day 1 around being a Robotaxi instead of taking a normal consumer car and trying to make the economics work.
This is a big deal.
Bc if Tesla can manufacture these at huge scale, keep them on the road for most of the day, and keep bringing the cost per mile down, then Uber and Lyft are going to be competing with the company that built the vehicle, the driver, and the network ALL AT ONCE.
And this was during launch week... with just ~45 Cybercabs, before this vehicle is anywhere close to mature scale. If Tesla can push that cost down further as the fleet grows to thousands and millions, while Uber and Lyft still have to pay a human being to sit behind the wheel…
I really don't see how these companies can survive... I think the days of Uber and Lyft are limited.
Show more


September @DallasFed Services Index fell to -1.8 vs. 2.3 est. & 4.2 prior; company outlook down to -3.2 vs. 3.0 prior; revenue down to -0.9 vs. 6.6 prior; employment up to 4.1 vs. 0.8 prior
Show more
