
Michael Green
@profplum99
Founder and CIO, Tier1 Asset Management |
1.4K Following 245.3K Followers
The second derivative of the rate of change is likely to decel. There’s no way any of this will work.

I have finally cracked how to use twitter for investing
I have a private list of “investors” who say stuff like “second derivative” and “sequential deccel” and “rate of change”
These are, bar none, the dumbest people on the app. They like the same stocks at the top and hate the same ones at the bottom
I wait for these people to say that a stock can’t work, and then I wait a little bit longer just to make sure they’re done vomiting. And then I buy it
Show more
Nope. It's magic.


"The" amazing thing I will disagree with. But yes, this is an easy form of elder abuse that goes on regularly.

The amazing thing about passive investing is that you can be a CFO of an absolute ZERO of a company, but if you're in an index, the ETF's HAVE TO BUY your stock so long as passive flows are positive. So, you just announce an ATM stock offering and buy yourself time given the dominance of cheap but dumb capital. And YES ... this is happening.
Show more
100% agree. Like many others, @t1alpha and @t1acapital are making rapid progress in moving local and only using cloud/frontier for hardest 5%. The local compute token supply is exploding.
From my perspective, it’s broadband 2.0, but possibly much worse, and will require pretty strong evidence otherwise.
Show more

I get it, there are nuances for tech-bros who are deep in the weeds. Everyone has an anecdote about why I’m wrong.
Take a step back and be a commodity-bro who’s seen enough supply/demand cycles. Tokens are a commodity. Currently, the token factories are out-stripping token demand. Pricing is the adjustment factor. Except token factories are mostly fixed-price businesses. They have take-or-pay. They have commitments. They will produce tokens at a loss rather than turn off.
I’m not saying that token demand is slowing. It’s still growing at astronomical rates. I’m saying that token production is now out-pacing demand. The cycle will turn when demand accelerates or token production slows. There’s like half a trillion $ of GPUs waiting to be installed. I don’t think token production slows anytime soon.
Yeah, I get it. Jevon’s and all. It’s great for AI consumers and innovators. But the guys owning token factories are gonna all go bust in the process, and that’s like $2T of capex to date. You cannot even restructure these things and crush the debt. They’re just stranded by new, and more efficient chips. They’re always going to be stranded by new chips. More efficient Models will strand the more expensive ones. It’s a race to the bottom against fixed costs. It’s the most godawful business misallocation I’ve seen in a while. Makes the Chinese look like prudent capital allocators🤣🤣
It’s like having iron rails when the new railroads run on steel. This bankruptcy cycle will be epic…
Show more

Wow. Did not expect this. A true loss both for scholarship and sanity.

We are deeply saddened to share the news that Perry Mehrling passed away this morning at the age of 67.
Perry was the father of the Young Scholars Initiative. He believed profoundly in young scholars, in their ideas, and in the importance of creating a community in which they could learn from one another and find their own voices.
Perry, you leave an enormous hole in our midst. Our hearts are aching, and we will miss you dearly.
The YSI community will carry your legacy forward. Your ideas, your generosity, and your commitment to generations of young scholars will remain with us.
Thank you for everything, Perry.
Show more
Appreciate the shout out, @ConvexityMaven.
But if you think I’m accepting the “may” qualifier, you know me not.
Harley and I are both highlighting the growing convexity risk that is created by yield levels affecting the price. Harley is spot on that the risk is a growing effective supply of duration and convexity risk created by a shift in both expected Fed behavior and changing sources of demand.
Since this supply increase is not matched by demand in passive bond products, Kevin Warsh is getting a signal of market structure, not macroeconomic information.
The Endgame approaches for a passive bond market with the potential for an inverse March 2000.
Show more


New Commentary.....
The CBOT Bond future is Negatively Convex such that a further rate rise could create the equivalent of Scott Bessent selling $110 Billion twenty-year bonds into the market.
Today, I detail the construction of this futures contract and posit that this could be a contributing factor to why interest rates have risen so quickly.
More specifically, be careful that 6% on the twenty-year rate could become a Convexity Vortex.
@profplum99 @LukeGromen @dampedspring @jam_croissant @biancoresearch @EconguyRosie @ErikSTownsend @tracyalloway
Show more
Thoroughly enjoying the latest wave of “It’s never different this time” nonsense. While I think AI is a bubble amongst bubbles, anyone who thinks AI is not already changing the economy is not paying attention.
Comparisons to total software or tractors remind me of the Barnes & Noble vs Amazon debates in 1999.
We have no idea what the future holds, but the world has changed. Better or worse remains to be “scene.”
Show more

FULL INTERVIEW: The Economist's Callum Williams says only about 25% of American businesses use AI four years in, when most people in 2023 would have bet on nearly all of them. Ask CFOs what AI has done for their bottom line, and he says it "basically balances to zero."
@econcallum is the senior economics writer at @TheEconomist. He joined @theojaffee and @schisofrenia to lay out why AI hasn't changed the economy yet and the signal he's watching for:
00:50 why AI hasn't changed the economy yet
01:38 why AI spread slower than the internet in business
03:05 why a laptop and ChatGPT isn't enough
04:20 the CFO surveys where AI's impact balances to zero
04:49 why cost will decide how fast AI spreads
06:11 the 25% stat, and the labor market signal he's watching
08:30 whether AI layoffs are real or just an excuse
09:43 robot McDonald's vs a fast food labor shortage
10:28 the COVID robot predictions nobody apologized for
11:55 the economic doom predictions that did come true
Show more

Who would have thought it possible?
From Aug 2023 YIGAF: “I am not dismissing the estimates entirely, but I would note that the incredible breakthroughs we are seeing in obesity treatments, cancer treatments, remote medicine, automated medicine, etc. are as likely to radically alter these estimated costs as the discovery of antibiotics did to tuberculosis.”
Show more

This is super macro important….in fiscal sustainability/ math for US. At a time when neither political parties have the will to practice fiscal austerity (except for tariffs), the creative way is to bring down longer term Medicare and Medicaid costs via less obesity.
Show more
Whatever could it be?

This is one of the WEAKEST US equity markets in history:
Only ~29% of the S&P 500's companies have outperformed the index over the last 3 years.
This is near the lowest reading since the 2000 Dot-Com Bubble peak, when this figure fell to ~25%.
The market has almost never been this concentrated.
Show more

First they mock ewe…
bill ackman on why large, boring companies now drop 25% in a day, something he says almost never happened when he started:
"a quarter of every american business, plus or minus, is owned by some combination of vanguard, state street and northern trust. when you shrink the float of a public company, the marginal buyer and seller is going to have more impact on the stock price."
"the marginal buyer and seller today is a citadel or a millennium. they operate with a large amount of leverage, very large gross books, and they're increasingly short-term."
"most investors are very short-term focused because they're compensated that way. they won't invest in a company unless they're confident the price is going to be higher on december 31st."
passive owns the float, pods set the price, and both are structurally unable to hold through a bad quarter. that inability is the opportunity.
Show more

Those "not restrictive rates" appear to be violating their characterization. Mortgage applications for purchase down to 1.3 per thousand age 25-54, down ~60% from 2021 and almost 75% from 2006.
"You'll own nothing" was right. The second part, not so much so.
Show more


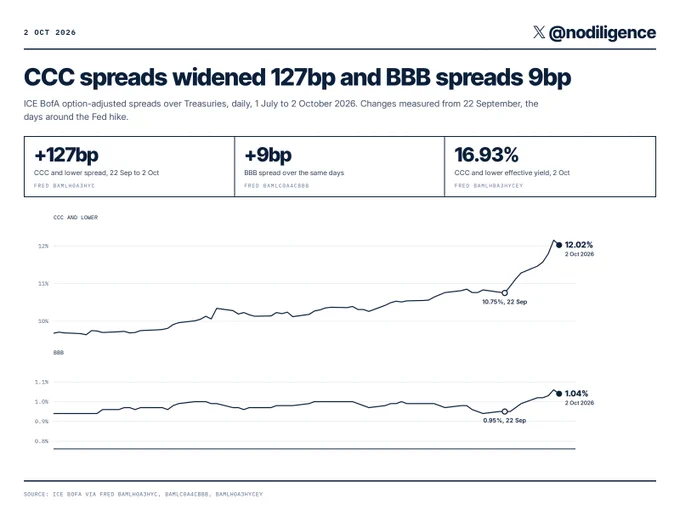
The CCC-shaped economy

CCC junk spreads went from 10.75% on 22 september to 12.02% on 2 october, about 127bp, and the CCC index yields around 17% now. BBB spreads moved 9bp over the same days, 0.95% to 1.04%. so the bottom of the credit market widened about 14x as much as the top.
the fed's hike is landing almost entirely on the weakest borrowers, and investment grade barely noticed. that's the market hyperscalers and the big AI issuers fund themselves in, so their bond deals keep clearing cheap while the companies that were already struggling pay for the hike
Show more
In the land of China, rates are falling because energy prices are rising. See how easy it is to create narratives?


Yields are rising in Europe as well because of higher energy prices. Global energy prices need to come down for global yields to come down.

I see everyone is playing “If I were King for just one day”
Truly incredible. Will shave at least 2/100ths of a second from my best time to the local bodega.
The super running shoe arms race is out of control.
Two runners that broke 2-hour marathon mark wore the Adidas Adizero Pro Evo 3. Now, Adidas has made a running shoe with gear shifts…that change the foam from stiff to soft.
Controlled by a runner’s watch for adjustments based on terrain or fatigue. Stiff bounces more for sprints while soft for cruising speeds.
***
OP link:
Show more

It’s been almost 100 years since the reform of non-recourse mortgages. I wonder how home prices would be different if you could never escape the liability.
My strong hunch is that many inherited houses will be sold in distress.
Show more

The biggest hurdle is the fact that house more likely is a liability not an asset. Second, is the liability mismatching, we will take a mortgage last 30 years against a job can fire you this Friday, and a job market full of fake job listings, most jobs are hiring applicants that are not able to differentiate their strength by a lot, thus, there is a limit how much more you can get paid, and makes it hard for you to get your foot into the door in absence of a labor shortage.
Also, cycles and trends matters. US population is aging, BOJ wants to get its money back. At this particular point to buy a house feels more like a future regret than a jackpot.
In 2024, I saw so many people crying on Tiktok how their mortgage payment had doubled since 2020. It turns out their insurance and property tax has skyrocketed.
Show more


A proposal you will only see from a politician who has not spent one moment in the private sector. Elect better.

For millions of young people across America, homeownership seems further out of reach than ever before.
Here's my proposal: we can help restore the dream of homeownership with a 5 to 1 federal match for first-time homebuyers saving for a downpayment.
Show more

Heckuva job, Kevin. You really showed them.











